At a glance
- Momentum for climate adaptation is increasing, but deployment lags. Adaptation that protects people and places from extreme weather events delivers benefits worth three times its cost on average. Yet globally, only $190 billion is spent annually on 20 proven measures, a third of the amount needed to meet developed-economy protection standards. Good economics alone don’t guarantee spending—deployment readiness depends on clear demand, capacity to act, and financing.
- Deployment-ready climate adaptation measures that protect lives and livelihoods represent a $460 billion annual opportunity by 2050. That’s 40 percent of the $1.2 trillion annual spending needed by 2050, when the global temperature could rise to 2°C above preindustrial levels on current emissions trajectories. More than two-thirds of this opportunity could be in high-income places, where the ability to pay and bankable projects are more prevalent. Much of the spending would go into measures like cooling, stormwater management, and irrigation.
- The majority of the remaining $690 billion of adaptation requires innovation to become deployable. Technological and financial innovation that reduces costs, particularly measures to cope with heat and drought in lower-income regions, could make an additional 40 percent of the $1.2 trillion deployable. Stronger incentives, clearer demonstrations of benefits, and improved delivery capabilities could make measures accounting for an additional 15 percent deployment ready. For the rest, demand already exists, but enabling bankability will require innovative revenue mechanisms and financing structures.
- Leaders can use an understanding of opportunities, barriers, and responses to enhance decision-making. Companies can build capabilities to assess and value adaptation, form implementation partnerships, and develop solutions to address the resilience needs of others where market signals are clear. Financial institutions can identify opportunities aligned with their risk appetite and can structure projects to improve bankability. Governments and philanthropies can strengthen demand for adaptation and can direct scarce capital toward closing affordability gaps.
By 2050, deployment-ready climate adaptation will grow, with innovation needed to address the majority of the remaining opportunity.
Note: Spending for 20 adaptation measures across heat, wildfires, drought, and flooding. Figures may not sum to 100%, because of rounding; percentages are rounded to the nearest 5%. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Observations of global temperatures indicate that Earth warmed by 1.1°C relative to preindustrial levels in the decade prior to 2020, which is what we refer to as “current climate conditions.”

Around the world, momentum is growing to plan for and protect people and places from extreme weather events, ranging from high temperatures to intense flooding. Governments and companies are seeking to understand their exposure to such events more proactively and develop potential responses to enhance resilience. The weather events of 2026 against the backdrop of a strengthening El Niño are further intensifying the focus on climate adaptation.1
Previous MGI research, Advancing adaptation: Mapping costs from cooling to coastal defenses, examined a set of 20 proven adaptation measures that protect people and assets against patterns of extreme weather.2 Early-warning systems give communities time to prepare for extreme weather events, irrigation helps farmers manage drought, and urban trees, cool roofs, and improved drainage reduce vulnerability to extreme heat and heavy rainfall. These measures are tried and tested, preventing disruption to economic activity, physical damage, and health impacts that can far outweigh their costs.
Yet the world has a “resiliency gap.” Many people are not protected from today’s extreme weather patterns. By our estimate, the world in 2020 spent only about a third of what was required to protect people exposed to climate hazards at standards established in advanced economies. And as the global temperature climbs, the pattern and occurrence of hazards are expected to shift, shaping future adaptation needs.
The resiliency gap is the conundrum at the heart of climate adaptation. If many measures are proven and economically viable, what prevents them from being deployed at scale? In this research, we identify barriers that prevent demand, implementation, and financing for adaptation and the responses that can help overcome them.
As mentioned in our prior research, some caveats are in order. Climate modeling is an evolving field, and complex phenomena come with uncertainties. We aren’t climate scientists, so we rely primarily on external climate models used in the sixth assessment report of the Intergovernmental Panel on Climate Change.3 Our findings aim to provide an order-of-magnitude economic analysis to help inform decision-making.
Ultimately, individuals, governments, and companies decide if, where, and how to adapt. Understanding where deployment is likely to take place going forward and which responses can enable harder-to-deploy adaptation can help companies and countries seeking to invest in resilience make informed decisions.
Adaptation is a good buy, but a resiliency gap persists
Despite overall attractive economics, climate adaptation is stymied by demand and financing barriers that prevent investment. These barriers crop up because widely shared benefits don’t always make a compelling case for households, companies, and governments to act or for capital providers to extend financing. Understanding these barriers helps explain why the resiliency gap persists and what shapes decisions about deploying adaptation measures.
Climate adaptation is gaining momentum
Recently, governments have stepped up adaptation planning, implementing measures and incorporating climate risk into public policy. The number of countries with national adaptation plans jumped from 84 in 2020 to 144 in 2026, a 71 percent increase, and countries that specified their financing needs in those plans more than doubled, from 14 to 29.4 Beyond planning, some governments are increasingly updating building standards to reflect changes in climate hazards. From 2020 to 2026, 79 national, state, and local codes around the world were updated for hazards such as wildfires and extreme heat, compared with just 19 from 2015 to 2020.5
Companies, too, are seeking to protect assets and people as well as increasingly playing a role in providing adaptation solutions. S&P Global reports that the share of the 9,242 companies in its Corporate Sustainability Assessment disclosing adaptation plans increased from 19 percent in 2022 to 46 percent in 2025.6 In a recent MSCI study, almost nine in ten companies reported undertaking resilience activities to protect their own operations, while about half reported revenue from resilience-related products or services.7
Nonetheless, a resiliency gap remains—and adaptation costs increase as Earth warms
Despite this momentum, a resiliency gap persists. In past MGI research, we studied 20 tried-and-true measures that are broadly applicable to diverse industries, economies, and demographic groups to protect people and places exposed to four categories of hazards—heat, wildfires, drought, and flooding.8 These include air-conditioning and cooling centers for heat, underground power cables to reduce wildfire risk, irrigation for drought, and levees and detention basins for flooding.9
We found that global annual spending on these 20 measures was about $190 billion in capital and operating costs in 2020.10 That spending provided some 1.2 billion people with protection at standards typically established in developed economies.11 Yet a resiliency gap persists. Achieving those standards to protect all 4.1 billion people exposed to a climate hazard today would cost almost three times more, or $540 billion annually.12 The gap is largest in low-income places, about $200 billion, or 2.7 times the gap in middle- and high-income places, $75 billion each.13
Going forward, adaptation needs could rise. Although countries made commitments to reduce emissions under the Paris agreement, the world is not on track to meet them.14 On current emissions trajectories, various estimates suggest the multidecadal mean surface temperature could rise to 2°C above preindustrial levels by 2050, with further warming expected thereafter.15 As global temperatures rise, more people and places are expected to experience climate hazards, sometimes with greater severity. Because some adaptation measures take years to build and remain in service for decades, decisions made today need to account for conditions through at least midcentury. Therefore, even as efforts to decarbonize continue, planning for the adaptation needed for a 2°C world is prudent, so we use it in this research as a planning scenario, not a forecast.
By 2050, some 8.9 billion people will live in places exposed – in line with developed-economy protection standards – to at least one climate hazard (though of course the impact of hazards varies).16 The annual cost of protecting them at developed-economy standards using the 20 measures we analyzed could rise to $1.2 trillion (Exhibit 1).17 About $190 billion a year of the increased costs would go into protection against increased severity of hazards in places currently exposed, while $430 billion annually would protect places newly exposed to hazards.
Protection at developed-economy standards at 2°C could cost $1.2 trillion annually by 2050.
Note: Spending for 20 adaptation measures across heat, wildfires, drought, and flooding. Figures may not sum to 100%, because of rounding. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
These figures are not projections of anticipated spending. After all, the world spends only $190 billion of the $540 billion that protecting against today’s hazards would cost annually. Rather, this calculation provides a benchmark based on developed-economy protection standards for decision-makers weighing future adaptation choices.
At 2°C of warming, more than half of the $1.2 trillion in adaptation spending would be for protection against heat, with active cooling measures like air-conditioning accounting for the largest share. This reflects the prevalence of heat stress, which is more prolonged and often more debilitating than briefer, less frequent heat waves. Protecting against drought would account for one-fifth, with about 15 percent needed for the installation and operation of irrigation systems. Building levees and detention basins to mitigate riverine flooding and flooding from excessive rainfall, as well as undergrounding power lines and investing in fuel management to reduce wildfire risk, would also require sizable investments, particularly in specific regions (Exhibit 2). Of course, careful planning would be needed to avoid maladaptation when implementing measures. For example, constructing a seawall or flood defense in one area may inadvertently increase flood risk elsewhere, while installing air-conditioning requires consideration of potentially significant emissions associated with energy use and refrigerants.18
Protection against heat and drought accounts for three-quarters of adaptation costs.
Note: This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Drought and wildfire figures include segments for early-warning systems at <1% of the total cost.
2Active cooling costs assessed using air conditioners, which are currently among the most effective measures for protecting against heat. Other measures like heat pumps, evaporative coolers, and fans also exist but have not yet widely scaled or are less effective.
While adaptation is often considered a matter for the public sector, our estimates indicate that half of the $1.2 trillion in adaptation costs could be investments typically made by private actors—consumers and companies—implementing measures such as active cooling and floodproofing to protect assets. About 30 percent of the costs for measures like sea dikes and early-warning systems could be publicly funded, while 20 percent could be implemented through either public programs or private initiatives for measures like irrigation (Exhibit 3).
About half of all adaptation costs are expected to require private action.
Note: Spending for 20 adaptation measures across heat, wildfires, drought, and flooding. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
Why is adaptation not happening despite being a good buy?
Implementing the 20 adaptation measures can generate benefits, measured as avoided damages, well beyond their costs. Benefits could include, for example, avoided damage to infrastructure or assets, avoided losses in labor productivity or crop yields, and avoided adverse health impacts. On average, these benefits are roughly three times costs in 2020, which could increase to about seven times costs at 2°C of warming.19 Resilience investments can also create value by extending the useful life of exposed assets, delaying costly replacement or retrofitting.20
Yet despite favorable overall economics, it isn’t a given that stakeholders will undertake this spending. After all, if adaptation decisions were based only on cost-benefit economics, there would be no resiliency gap today. Clearly, even when economics are compelling at an economy-wide level, the financial case can still be weak for an individual actor—a household, a company, or a government—expected to pay.
For example, a sea dike may prevent losses worth many times its cost across an urban area. Residents, businesses, landowners, and insurers would all benefit from the measure, and so the benefit-to-cost ratio for society at large may be high. However, the financial case for the implementer could be weak.21 The public agency responsible for constructing a dike is unlikely to receive a dedicated revenue stream from the project to recoup its costs, and numerous unrelated demands are competing for its money and attention. Financial institutions, similarly, may find it difficult to invest in assets not associated with a direct revenue stream.
Thus, the resiliency gap stems less from the macroeconomics of adaptation than from barriers that block implementation by individual decision-makers. For adaptation to advance to deployment, two conditions must be met. A household, company, or government must want and be able to implement it, and a bank or an investor must be willing to finance it on acceptable terms. Failure to meet the first condition creates demand barriers, and failure to meet the second puts up financing barriers.
Importantly, demand and financing barriers can arise from the same underlying economic frictions—including resource constraints, information gaps, and difficulties in assessing and pricing risk—and they often reinforce one another. For example, the underlying economic challenge of limited resources of households or governments can create competing spending priorities for implementers, which is a demand barrier, and counterparty risk for funders, which is a financing barrier.22
Ultimately, households, companies, and governments decide what to spend on. Even when they can finance and implement adaptation, they may choose to forgo it and bear the risk. Nonetheless, understanding the demand and financing barriers that could hold adaptation back can help improve decision-making.
Four demand and four financing barriers stand in the way of adaptation
Demand for adaptation can be weak for several reasons. Those seeking to implement adaptation measures may have more pressing uses for limited resources, underestimate the benefits, lack incentives to invest, and face practical challenges in execution.
Competing spending priorities. Households, companies, and governments may value adaptation but prioritize other needs when resources are constrained. For example, providing developed-economy standards of climate protection at 2°C would cost roughly $130 per person annually on average.23 In Bangladesh, $130 is roughly half of average monthly household income, more than 40 percent of which is spent on food.24 In advanced economies, adaptation may cost about 0.5 percent of GDP exposed to climate hazards, while in emerging economies, it could cost more than 2.0 percent. These trade-offs explain why the resiliency gap in 2020 was concentrated disproportionately in lower-income places.
Gap in perceived benefits. The benefits of adaptation can be difficult to see until disaster makes the risks and costs of inaction tangible. This can reflect limited awareness of the risk a hazard poses, uncertainty about whether it will occur or how severe it could be, or uncertainty about whether a particular adaptation measure will work as intended. Following the 2025 Los Angeles wildfires, for example, government agencies and businesses across California increased investment in wildfire resilience.25 As time passes, the influence of significant events on adaptation behavior can diminish.26
Misaligned incentives. Those who pay for adaptation do not always capture its benefits, weakening incentives to invest. For example, under traditional funding models, all taxpayers may finance projects such as sea dikes while the direct benefits of dikes accrue most in specific coastal communities.27
Execution challenges. Large-scale adaptation can require complex coordination of assets, stakeholders, and institutions, creating delays, roadblocks, and even cost overruns. For example, the Room for the River program in the Netherlands, designed to improve safety for four million people living in river deltas, required more than a decade of coordination and consultation by multiple levels of government and stakeholders.28
Financing barriers arise when capital providers are uncertain whether projects can be originated efficiently, generate sufficient revenue, repay financing, and perform as expected. We consider four types of financing barriers.
Operational risk. Lenders may face transaction-cost and intermediation frictions that make projects costly to originate, aggregate, monitor, and finance. In Ahmedabad, India, thousands of individual cool-roof installations were too small for conventional lenders to finance one by one. Local community organizations and municipal actors like the Ahmedabad Municipal Corporation and Mahila Housing Trust helped aggregate projects so financing could reach households.29
Revenue risk. Adaptation investments may generate substantial dispersed or indirect societal value but can lack predictable, dedicated revenue streams to repay investors. Miami Beach, for example, needed to finance pump stations, drainage upgrades, tidal controls, and raised roads to address chronic flooding, but these investments would not generate dedicated revenue. The city established a stormwater utility fee paid by property owners, creating a predictable revenue stream to support borrowing and continued investment.30
Counterparty risk. Lenders may be constrained by credit market imperfections when they doubt a borrower’s ability to repay, making them reluctant to finance projects on acceptable terms. For example, Bangladesh had limited access to affordable commercial financing for rehabilitating roughly 850 kilometers of coastal embankments that protect against flooding. Instead, it relied on the World Bank’s International Development Association concessional finance, securing $400 million for the first phase with a 40-year maturity. The association’s preferred-creditor status helps it offer terms unavailable in commercial markets.31
Technology risk. Uncertainty over technology maturity and performance can limit investors’ ability to assess and bear risk. Limited performance data or difficulty in quantifying resilience benefits at scale can stymie adoption. Singapore’s NEWater program, for example, grappled with uncertainty over whether high-quality reclaimed water could be produced at scale. PUB, the national water agency, built a full-scale demonstration plant to test the technology and validate water quality and reliability. Once the technology was proven, the Singapore government could develop public–private partnerships to support some additional plants, which were operated under long-term contracts between PUB and private companies.32
Demand and financing barriers together determine deployment readiness
Different adaptation measures face different combinations of demand and financing barriers. For example, municipal levees and fuel management in low-income places may confront counterparty risk related to financing but have different demand barriers. Levees often compete with other spending priorities, while fuel management may be constrained by underappreciated wildfire risk, making its benefits unclear or intangible.
Other measures may have minimal demand barriers but different financing barriers. In middle-income places, implementing air-conditioning may be stymied by few financing barriers, while early-warning systems may encounter revenue risk because they lack the predictable cash flow lenders typically require (Exhibit 4).
The same demand barrier can mask very different financing constraints.
Note: This analysis maps illustrative adaptation measure and demographic-group examples to their primary demand-side and financing barriers. Examples are not exhaustive. Empty cells are combinations that do not typically occur, based on the categorizations used in our analysis.
And in practice, multiple barriers may constrain a single measure. Flood infrastructure in low-income places may face counterparty risk if the implementing agency cannot meet lenders’ credit requirements as well as revenue risk if the project lacks the cash flow to service financing. We focus on the primary demand and financing barrier for each of the 20 adaptation measures in our research, while recognizing that multiple barriers may need to be addressed.
What could the world spend going forward?
Not all climate adaptation investments are equally ready to move forward. Some can proceed with relatively little friction because implementers have the resources, incentives, and capabilities to act and financing is readily available. In other words, they are deployment ready, with minimal demand and financing barriers.
Others must overcome significant obstacles before investment can happen. As adaptation needs grow, there is no guarantee that they will translate to deployment-ready adaptation opportunities. The mix of measures that meet the threshold of minimal demand and financing barriers will shape where adaptation is likely to occur without targeted interventions and the scale of the resilience challenge that remains.
Adaptation measures with a value of $460 billion could be deployment ready by 2050
For the 20 adaptation measures we studied, total annual adaptation costs to protect the world at developed-economy standards could rise from roughly $540 billion in 2020 to $1.2 trillion at 2°C through 2050.
How much of that could be deployment ready? By our estimate, deployment-ready adaptation could reach about $460 billion a year, or 40 percent of the $1.2 trillion needed by 2050, compared with about $190 billion spent today.33 These measures can protect people from heat, wildfire, drought, and flooding, and safeguard homes, livelihoods, businesses, and economies.
Our analysis of deployment readiness is based on a granular assessment of the demand and financing barriers that stand in the way of deployment of 20 adaptation measures across demographic groups by level of income and urbanization as well as across regions (see sidebar “Our research methodology”). While not a definitive prediction, this assessment offers a way for stakeholders to better understand where deployment could occur without targeted responses and where adaptation markets could develop. This creates an opportunity for companies providing adaptation solutions and capital providers financing their deployment.
Our analysis finds that more than two-thirds of the $460 billion of deployment-ready measures by 2050 will be in high-income places, spanning measures like active and passive cooling, stormwater management, early-warning systems, and irrigation.
By 2050, much of the growth in deployment-ready opportunities relative to current spending is expected to occur where increasing climate exposure coincides with an ability and willingness to pay. For example, as heat stress and heat waves become more frequent and prolonged in markets where households and businesses have sufficient purchasing power, demand for air conditioners and fans is likely to increase, as it did in Europe in the unusually hot summer of 2026.34 Similarly, more frequent and widespread drought in higher-income places could increase demand for irrigation and other agricultural resilience measures where stakeholders may have a higher ability to pay and where the measures can generate revenue by increasing agricultural output and supporting financing.
The deployment-ready market could be bigger still when considering the wider universe of adaptation.35 Beyond the 20 measures in our analysis, deployment-ready measures could develop, for example, in sector-specific activities, such as increasing the resilience of power systems, and across the broader adaptation ecosystem, including supply chain resilience and hazard-management software (Exhibit 5).
At 2°C, a $460 billion deployment-ready opportunity in 20 cross-sectoral measures is part of a wider market for adaptation solutions.
- Active cooling and heat-management solutions in higher-income places
- Irrigation solutions in higher-income rural areas
- Stormwater resilience solutions in high-income cities
- Building floodproofing in higher-income places
- Power-system and grid resilience
- Transportation and infrastructure hardening, elevated infrastructure, resilient ports
- Water-system resilience, desalination, drought-resilient water supply
- Cold chain logistics
- Climate-resilient supply chains and diversified sourcing
- Upstream manufacturing of cooling solutions
- Installation, maintenance, and retrofit services
Note: Deployment-ready opportunity estimated based on 20 tried-and-true adaptation measures examined in Advancing adaptation; this is not an exhaustive set of cross-sectoral adaptation measures. Other examples include changing working hours, wearable technology, reforestation, and distributed backup power. Size of circles is illustrative. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
Several tailwinds could further bolster deployment-ready adaptation. The occurrence of extreme weather events and growing risk awareness could make the benefits of adaptation more tangible for implementers. Economic development could increase disposable incomes and the ability to pay for adaptation. Improving cost-benefit economics as hazards intensify could further strengthen incentives to adapt, as could the external environment through, for example, policy shifts or the impact of risks on insurance premiums. Moreover, broader investments in areas such as energy reliability and supply chain resilience could also provide adaptation benefits, even if undertaken for other purposes.
The majority of adaptation costs at 2°C could face deployment barriers
At 2°C, roughly 60 percent of the cost of adaptation measures to protect to developed-economy standards would still encounter demand or financing barriers. These measures represent an additional $690 billion of adaptation costs, but their potential to translate from needs to deployment that protects lives and livelihoods, particularly for vulnerable communities, and a commercially addressable market is contingent on addressing underlying barriers (Exhibit 6).
At 2°C by 2050, $690 billion of adaptation costs could be harder to deploy.
Note: Spending for 20 adaptation measures across heat, wildfires, drought, and flooding. Values are rounded to the nearest $10 billion. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Operational risk can include transaction and intermediation costs associated with originating, aggregating, monitoring, or financing projects; this analysis captures only small-ticket financing costs.
2Insufficient societal returns and technology risk are not assigned costs, because all 20 adaptation measures analyzed have benefit-to-cost ratios >1.5 and are proven, market-ready solutions.
Affordability is a central constraint, with measures costing roughly $440 billion confronting competing spending priorities and counterparty risk. This combination of barriers is prevalent in lower-income regions where heat and drought exposure are high but households, businesses, and governments often have less ability to pay and more limited access to affordable finance. Residential cooling illustrates this challenge. Measures like air-conditioning offer compelling health and productivity benefits, but many households may be unable to afford the equipment or ongoing electricity expense, given other essential spending requirements or may lack access to electricity altogether.
Measures constrained primarily by execution challenges or a combination of misaligned incentives and revenue risk account for the next two largest categories of spending, each roughly $50 billion.
In the first category, willingness and ability to pay exist, but practical capacity to act is limited by required stakeholder coordination. White roofs in high-income cities, for example, can require coordination of large numbers of buildings and property owners, making government facilitation key to implementation. These measures may be closer to becoming commercially addressable if execution constraints can be resolved.
In the second category, those bearing the costs of a measure may capture only part of its benefits while the measure itself generates insufficient revenue to support financing. Levees in higher-income towns are one example. Translating benefits into willingness to pay and financeable revenue is a prerequisite for commercial deployment.
The remaining roughly $150 billion of adaptation costs at 2°C is distributed across measures with other combinations of demand and financing barriers. (Note that this analysis excludes technology risk because we focus on tried-and-true adaptation measures, although it could still become a constraint to the deployment of other measures, which we discuss in Chapter 4.)
Demand and financing barriers vary widely depending on the hazard
Primary demand and financing barriers vary by hazard, reflecting the economics of the underlying measures to protect against different hazards and the places where they must be deployed (Exhibit 7). Measures that generate direct revenue or productivity gains often face different barriers than those with the main benefit in avoiding future losses, while the ability to pay and access to finance vary substantially by location.
Each hazard has distinct barriers to adaptation.
Note: This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Includes other combinations of barriers, for example, misaligned incentives and minimal barriers.
Heat adaptations are split roughly evenly between measures having limited barriers and those with significant demand and financing constraints. Among constrained measures, the most common combination of barriers is competing spending priorities and counterparty risk. This reflects where heat adaptation is needed. In higher-income places, implementers often have resources or the ability to use financing to invest in cooling. But lower-income populations, whose limited ability to pay and weaker creditworthiness translate to higher demand and financing barriers, also face substantial heat exposure.
Wildfire adaptation is primarily constrained by gaps in perceived benefit, because investment decisions about measures like fuel management and underground power lines can depend heavily on the perceived likelihood and consequences of catastrophic events that may not occur every year. This is true at all income levels. Indeed, wildfire weather is the hazard against which high-income places have the largest resiliency gap today relative to other hazards.36
Nearly half of the adaptation measures related to drought in our analysis have limited barriers. Measures like irrigation can increase agricultural yields and generate revenue streams that support demand and financing, while drought adaptation costs are disproportionately concentrated in higher-income regions. Although drought accounts for about 20 percent of adaptation costs globally at 2°C, it represents 30 percent of adaptation costs in higher-income regions such as the EU-30 and North America.37 This concentration in places with greater access to capital helps explain why a comparatively large share of drought adaptation faces limited barriers.
Misaligned incentives often stymie implementation of flood protection infrastructure because benefits accrue to property owners, businesses, and residents in flood-prone areas while the costs are typically shouldered by the broader community. Revenue risk can compound this challenge because flood-protection infrastructure often lacks cash flow and may require mechanisms such as user fees, value capture, and beneficiary payments to monetize its benefits.
Barriers to adaptation vary sharply by region
Each region faces different hazards, requires different climate adaptation measures, and varies in its ability to pay for and finance those measures. Lower-income regions face greater adaptation costs relative to residents’ average income as well as greater deployment barriers. Higher-income regions need to spend less as a share of residents’ average income but still encounter demand and financing barriers. Differences in income, hazard exposure, and the measures required to adapt help explain why deployment readiness varies between regions.
Lower-income regions have higher adaptation costs and more barriers to deployment
MGI’s previous analysis on adaptation found that low-income regions currently have larger resiliency gaps. The disparity is greatest in protection from heat. For example, some 60 percent of India’s population and 30 percent of Nigeria’s live in places that already experience heat stress.38 Yet air-conditioning coverage in these countries is scant, at about 10 percent in India and 3 percent in Nigeria.39 By contrast, in the United States, just 4 percent of the population may experience heat stress today, but air-conditioning coverage exceeds 90 percent.
At the same time, lower-income regions are also expected to have higher adaptation costs to protect to developed-economy standards relative to their GDP going forward. At 2°C of warming, adaptation to protect to developed-economy standards would cost an estimated 2.0 to 3.0 percent of GDP in India and Sub-Saharan Africa, compared to just 0.3 to 0.5 percent of GDP in higher-income regions such as North America, the EU-30, and Advanced Asia.40
But higher adaptation costs are only part of the challenge for lower-income regions. Their adaptation needs are more likely to face demand and financing barriers. This helps explain the large resiliency gap in these regions today and lower share of adaptation costs linked to measures that are deployment ready going forward. Less than 20 percent of the adaptation investment needed in Sub-Saharan Africa and India at 2°C is expected to be deployment ready, compared with more than half in higher-income regions (Exhibit 8). Put differently, the regions that need greater protection relative to their capacity to spend also face greater barriers to deploying it.
More than 60 percent of adaptation costs at 2°C in EU-30 and MENA could be deployment-ready, versus less than 20 percent in Sub-Saharan Africa.
Note: This analysis assigns annual operating and amortized capital costs for 20 adaptation measures used to protect to developed-economy standards at 2°C to deployment readiness by region. Adaptation measures with societal benefit-to-cost ratios <1.5 are excluded. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Deployment-ready adaptation has clear demand signal and is market ready for financiers.
2EU plus Norway, Switzerland, and UK.
The mix of demand and financing barriers varies by region
In lower-income regions with large populations, much of the adaptation needed is for protection against heat, including cooling measures that require households, companies, and governments to devote resources to adaptation when they have other pressing needs. Competing spending priorities are the biggest demand barrier in India and Sub-Saharan Africa, accounting for roughly 80 percent of adaptation costs that face a demand barrier (Exhibit 9).
Lower-income regions face competing spending priorities and counterparty risk, while others face misaligned incentives and revenue risk.
Note: Combines demand-barrier and financing-barrier decompositions of the same annual adaptation cost pool for 20 measures used to protect to developed-economy standards at 2°C. Adaptation measures with societal benefit-to-cost ratios <1.5 are excluded. Figures may not sum to 100%, because of rounding. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Exposure encompasses four categories of hazards: heat, wildfires, drought, and flooding. Hazards are defined based on protection standards established in developed economies.
2EU plus Norway, Switzerland, and UK.
Adaptation in high-income regions also confronts demand barriers, but of a different nature. In regions such as Advanced Asia and the EU-30, where adaptation costs are primarily related to large flood-protection infrastructure, misaligned incentives are more common because the public entities funding protection may find it difficult to directly capture the benefits or impose fees on all who benefit.
Some barriers cut across income levels. Gaps in perceived benefits can constrain wildfire protection everywhere, while execution challenges can arise for widely dispersed adaptation measures such as residential white roofs.
Even where demand barriers are limited, financing barriers can still prevent deployment. The primary financing constraint varies across regions. Counterparty risk is the largest financing barrier in lower-income regions, constraining implementation of measures accounting for roughly 75 percent of adaptation costs in Sub-Saharan Africa, India, and Emerging Asia, compared with only about 10 percent in higher-income regions.41 Higher-income regions, by contrast, are more likely to face revenue risk. In these regions, those wishing to implement adaptation may be willing and creditworthy, but investments based on avoided losses for measures like detention basins and sea dikes may not generate predictable cash flow against which private capital can easily lend, making financing more challenging.
Moving adaptation beyond barriers toward deployment
Experience demonstrates that barriers to climate adaptation can be overcome. Many measures are now an integral part of their environments—the Thames Barrier in London, for instance, and the MOSE Project in Venice. Implementing more of them requires governments, companies, and communities to better collaborate to reduce costs, resolve complex engineering and technical challenges, create revenue streams, and mobilize innovative financing to close funding gaps. Understanding what has enabled successful adaptation can help identify how to move more measures from identified need to actual deployment.
Targeted responses can overcome barriers to adaptation deployment
As noted previously, the deployment-ready opportunity across the 20 measures we analyzed amounts to $460 billion annually by 2050.
Of course, this opportunity is contingent on measures that are currently deployment ready maintaining that status as they scale to respond to increasing adaptation needs. The remaining $690 billion, or 60 percent of the $1.2 trillion in total annual adaptation costs at 2°C, is more challenging, stymied by demand or financing barriers, often in combination. Without targeted responses, a substantial share of adaptation needs may be unmet, many of them in the communities most exposed to climate hazards. A common pattern of responses emerges from our analysis of barriers (Exhibit 10).42
Patterns of adaptation responses emerge from the combination of demand and financing barriers.
Note: Spending for 20 adaptation measures across heat, wildfires, drought, and flooding. This analysis is based on warming levels likely under current emissions trajectories, which project that the global temperature is likely to rise 2°C relative to preindustrial levels sometime in the next three decades (measured based on multidecadal average temperatures). This analysis relies on existing and established climate models and techniques, including from the sources below.
1Cells without values are combinations that do not occur, based on the categorizations in our analysis.
2Technology risk is not assigned costs as part of this analysis, because all 20 adaptation measures analyzed have benefit-to-cost ratios >1.5 and are proven solutions with limited technology risk.
Innovating to reduce costs could address by far the largest challenge. Innovation could make $440 billion of measures, or 40 percent of the $1.2 trillion of annual adaptation costs at 2°C, deployment ready by reducing affordability barriers.
An additional $210 billion, or 15 percent of the total annual costs, requires increasing willingness or ability to act. Of this, roughly $80 billion annually could address building capability and coordination, for example building detention basins and other flood infrastructure in higher-income regions where coordination between different government departments is required. Realigning incentives, for example, for levees and irrigation systems in higher-income rural areas, could eliminate barriers to roughly $70 billion annually. Demonstrating value, primarily for wildfire protection measures, could move another $60 billion annually of adaptation measures toward deployment.
For the remaining 5 percent, demand broadly exists, but financing remains constrained. Enabling bankability could address roughly $40 billion annually, creating revenue streams with innovative structures to support financing. Such structures could support early-warning systems in middle-income places, where benefits do not naturally translate into project revenues, for example. Proving feasibility can help newer technologies attract financing, although we have primarily focused on measures with established track records in this research.
In reality, the implementation of any given adaptation measure is local and may require several of these responses to work together, depending on the stakeholders involved and the conditions for implementation.
Select examples of how barriers have been overcome
Below, we lay out potential actions for decision makers, drawing on an understanding of barriers and examples of adaptation from around the world. This list of actions can be a starting point for determining whether and how to best implement adaptation efforts and evaluate trade-offs and synergies with other priorities.
Innovating to reduce costs is a priority when adaptation must compete with essential spending priorities because high costs put it beyond the reach of potential implementers or high borrowing costs make financing hard to secure. The affordability challenge for households and businesses may extend beyond the upfront capital or financing costs for resilience. Adaptation measures may increase ongoing expenses, such as electricity bills from air-conditioning. Left unaddressed, unaddressed climate risks can also raise costs, such as insurance premiums or post disaster recovery expenses. These challenges are particularly relevant in lower-income communities where households and governments may value adaptation but lack the resources to pay for it.
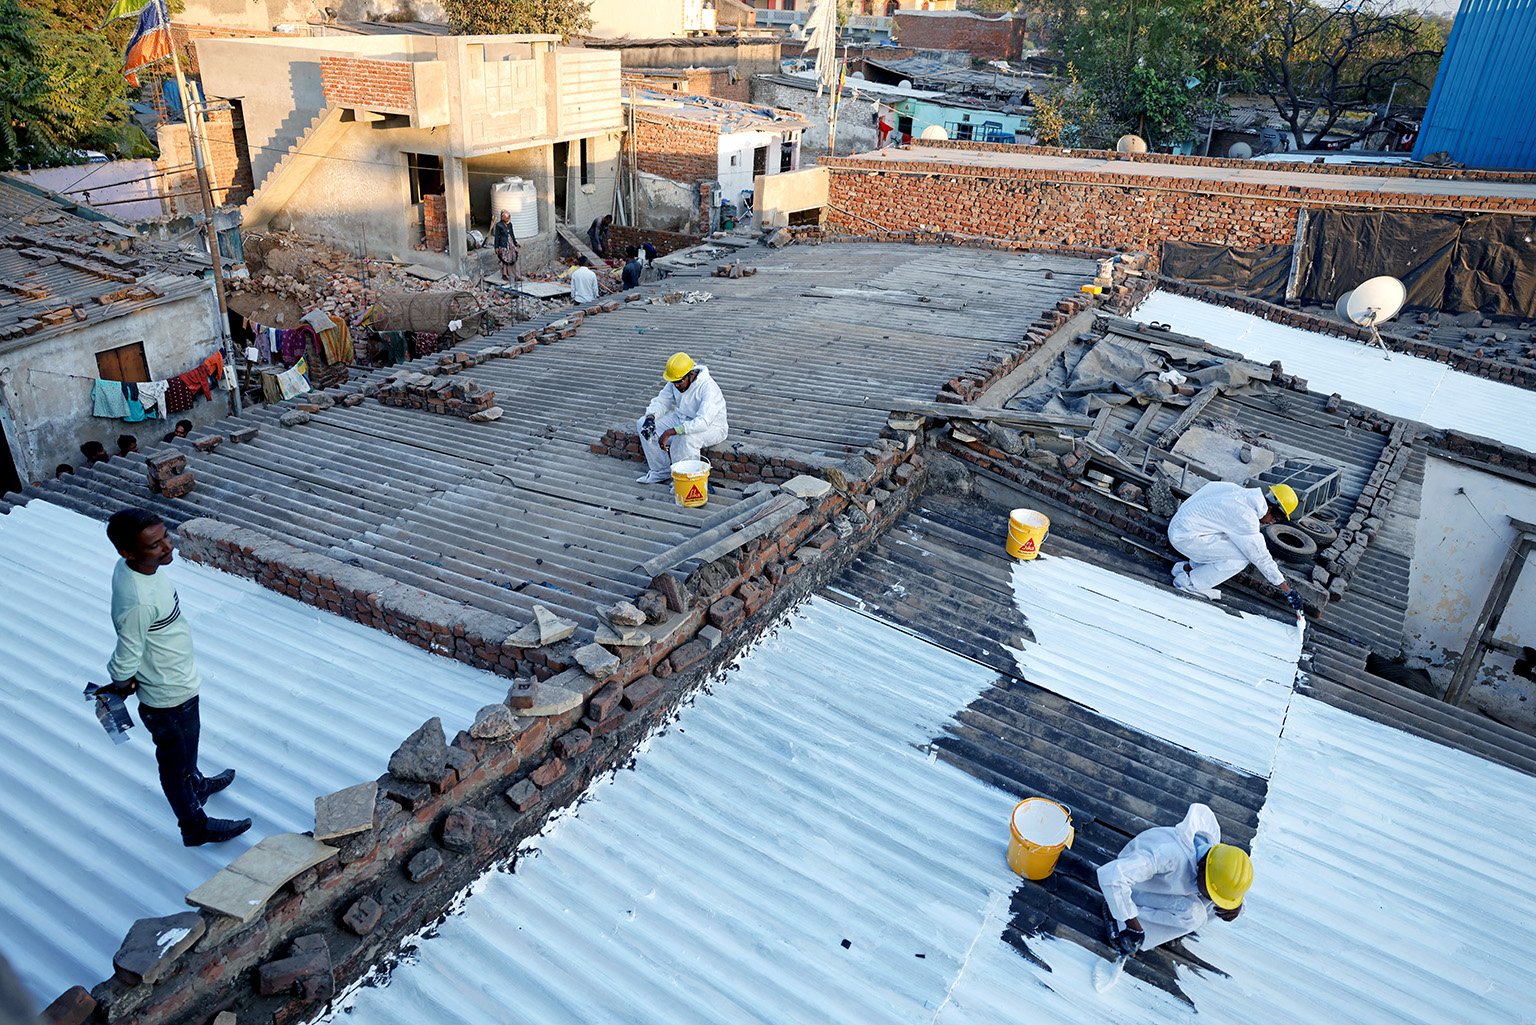
Case example 1: Ahmedabad cool roofs, India
After a heat wave in 2010 when the temperature reached 46.8°C, Ahmedabad became the first city in South Asia to launch a heat action plan.43 The 2013 plan combined an early-warning system with longer-term measures to reduce heat exposure, including so-called cool roofs, which use reflective materials like white paint to reduce heat absorption and lower indoor temperatures.
For low-income households, competing spending priorities can constrain demand for cool roofs because limited resources make it difficult to prioritize adaptation over other essential spending. Limited household budgets and access to affordable finance can create counterparty risk, making it hard for a family to borrow for adaptation. The small size and dispersed nature of household-level cool-roof investments also can create operational risk because lenders would have to originate and finance many small transactions.44
The Ahmedabad Municipal Corporation addressed competing spending priorities and counterparty risk by partnering with the Mahila Housing Trust, a grassroots organization focused on housing and urban resilience in low-income communities. Together they provided subsidies and credit, drawing on public, corporate, and philanthropic funding secured by demonstrating the impact of cool roofs. This reduced up-front costs for households and reliance on conventional borrowing. To address operational risk, Ahmedabad and the trust launched a municipal program that aggregated deployment in thousands of homes, creating sufficient scale to make implementation and financing efficient.45 Where installed, the reflective coatings have cut indoor temperatures by roughly 2°C to 5°C compared to conventional roofs, a meaningful margin for households lacking access to cooling. In 2020, Ahmedabad expanded the rollout of cool-roof coatings to more than 15,000 roofs in low-income neighborhoods and 1,000 government buildings.46
Example actions for consideration
- Developing lower-cost and more effective solutions. Lower-cost technologies and more efficient designs such as for cooling or irrigation systems can reduce the resources required to achieve a given level of protection.
- Reducing costs through creating best practices and economies of scale. Leveraging best practices from others and repeated implementation across projects can enable standardization, learning, and more efficient delivery. In some instances, larger-scale community-based approaches could also prove to be more cost-effective, for example by pooling demand to help achieve scale, spread fixed costs, and reduce unit costs.
- Providing targeted financial support. Targeted grants, subsidies, and concessional and blended finance can lower up-front costs and make adaptation more affordable (see sidebar “How can blended finance advance adaptation?”).
Building capability and coordination becomes a priority when adaptation requires complex planning and delivery by multiple stakeholders and institutions. This is particularly relevant for large infrastructure programs with fragmented responsibilities and lengthy approvals that can impede progress.
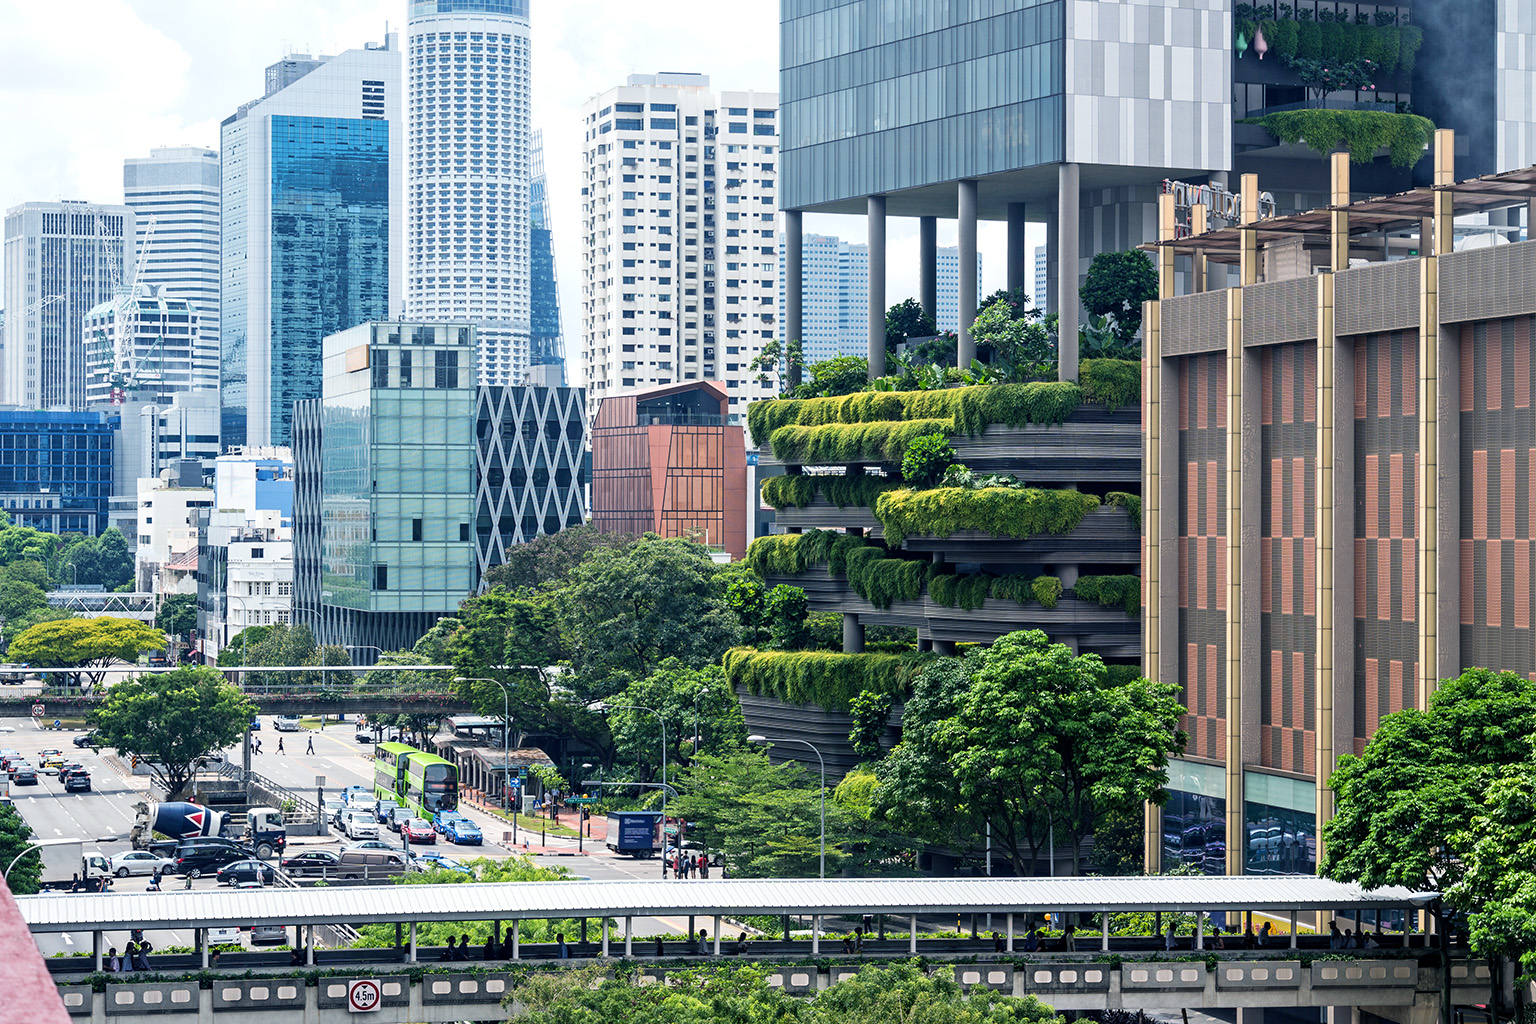
Case example 2: Marina Bay district cooling, Singapore
As Singapore developed Marina Bay into a major commercial district, the government wanted a more efficient way to meet the area’s growing cooling needs. Rather than relying on separate air-conditioning units in each building, Singapore developed a centralized district cooling network to move chilled water through a network of pipes beneath multiple building developments. The system began operating in 2006 and has expanded as the district has grown.
The primary barrier was execution. District cooling required building shared infrastructure in collaboration with individual developers as well as coordination with utilities, regulators, and a specialized system operator. Individual buildings would need to depend on a common network for an essential service, making system reliability and common technical standards critical.
Singapore coordinated infrastructure, delivery, and adoption from the outset, embedding district cooling into Marina Bay’s development. The government incorporated district-cooling pipes into the district’s common services tunnel, built by the government for utility infrastructure to give buildings access to shared infrastructure. It licensed a subsidiary of SP Group, which runs Singapore’s grid, to build, operate, and maintain the system, concentrating technical expertise and responsibility in a single dedicated operator. Standardized connection requirements made it easier to add buildings as Marina Bay developed, and early land-sale conditions required commercial buildings to connect to district cooling, coordinating adoption with the network’s expansion and reducing investment risk. The system has operated without supply interruptions, using as much as 40 percent less energy than conventional building-level chiller plants.47
Example actions for consideration
- Strengthening project preparation. Technical assistance and project-preparation support can turn complex adaptation plans into projects that are ready to implement.
- Building dedicated delivery capacity. Established teams can coordinate responsibilities with agencies, utilities, contractors, and communities.
- Streamlining approvals and procurement. Simplified permitting and procurement processes can reduce delays and move projects forward more efficiently.
- Standardizing for scale. Standardized designs and contracts can make projects easier to replicate across multiple sites.
- Linking funding to progress. Milestone-based payments can tie funding to delivery progress and reduce the risk of projects stalling.
Realigning incentives becomes a priority when those bearing the costs of adaptation do not capture enough of the benefits to justify action. This is particularly relevant for measures that deliver benefits spread across communities or assets while costs are concentrated among specific governments, businesses, landowners, or households.
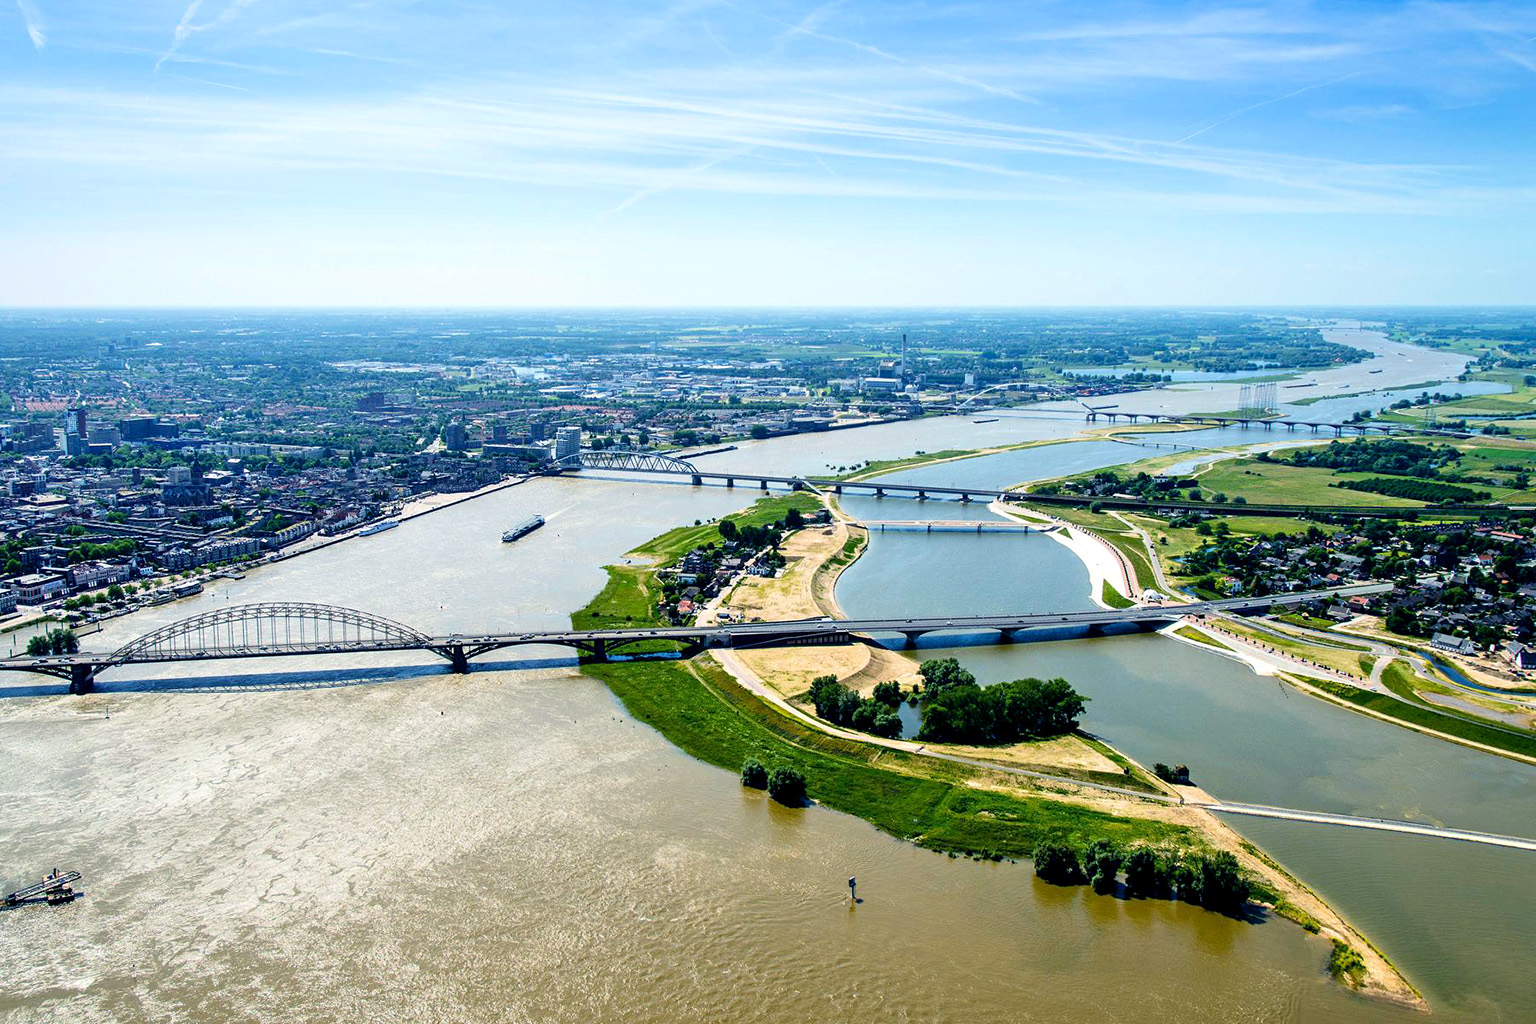
Case example 3: Room for the River program, Netherlands
The Netherlands has long relied on dikes to protect against river flooding, but dangerously high river levels in 1995 exposed the limits of continually raising their levels after 250,000 people were evacuated amid fears the dikes could fail. The Netherlands decided that rather than continuing to try to confine rivers, it would give them more room to accommodate periods of extreme flooding.
However, misaligned incentives created a demand barrier. Giving the rivers more room would protect millions of people, but some of the most immediate costs fell on landowners and communities that would need to give up land or change how it was used. The plan also faced an execution barrier, requiring coordination of national and regional governments, municipalities, water boards, landowners, and communities on more than 30 projects.
To realign incentives, the Netherlands compensated affected landowners and farmers, buying properties at market value, helping farmers find new farmland, and, in some cases, supporting residents who had been unwilling to move as they relocated to higher ground nearby. To address the execution barrier, the national government set overall flood-safety objectives and gave local authorities and communities flexibility to design solutions suited to specific conditions. The central program maintained coherence across projects, standardized project procedures, ensured knowledge sharing, and evaluated proposal options using a common planning tool. Even with this extensive coordination, the program took more than a decade to implement.48
Example actions for consideration
- Developing compensation mechanisms for those bearing the costs. Measures like relocation support and payments to landowners who host protective infrastructure can reimburse landowners, households, and businesses that may otherwise disproportionately bear costs to deliver broader community benefits.
- Implementing beneficiary payment schemes for adaptation. Under these mechanisms, those receiving adaptation benefits pay at least a portion of the costs.
- Capturing value created by adaptation. Mechanisms such as special assessments that charge benefiting property owners, development charges on new construction, and land-value capture can recover a portion of land and property values to help fund investments in adaptation.
- Creating resilience standards and incentives. Hazard-aligned building codes, zoning regulations, and other incentives are among the approaches jurisdictions have taken to encourage investments in resilience or steer development away from high-risk locations.
Demonstrating value is important when those who would benefit from adaptation underestimate the risks they face or do not fully recognize its value. This can be especially challenging when the occurrence and severity of hazards are uncertain. For example, wildfire weather may occur regularly, but whether a wildfire starts and causes losses remains uncertain and depends on many factors, making the value of investment in protection less immediately apparent.
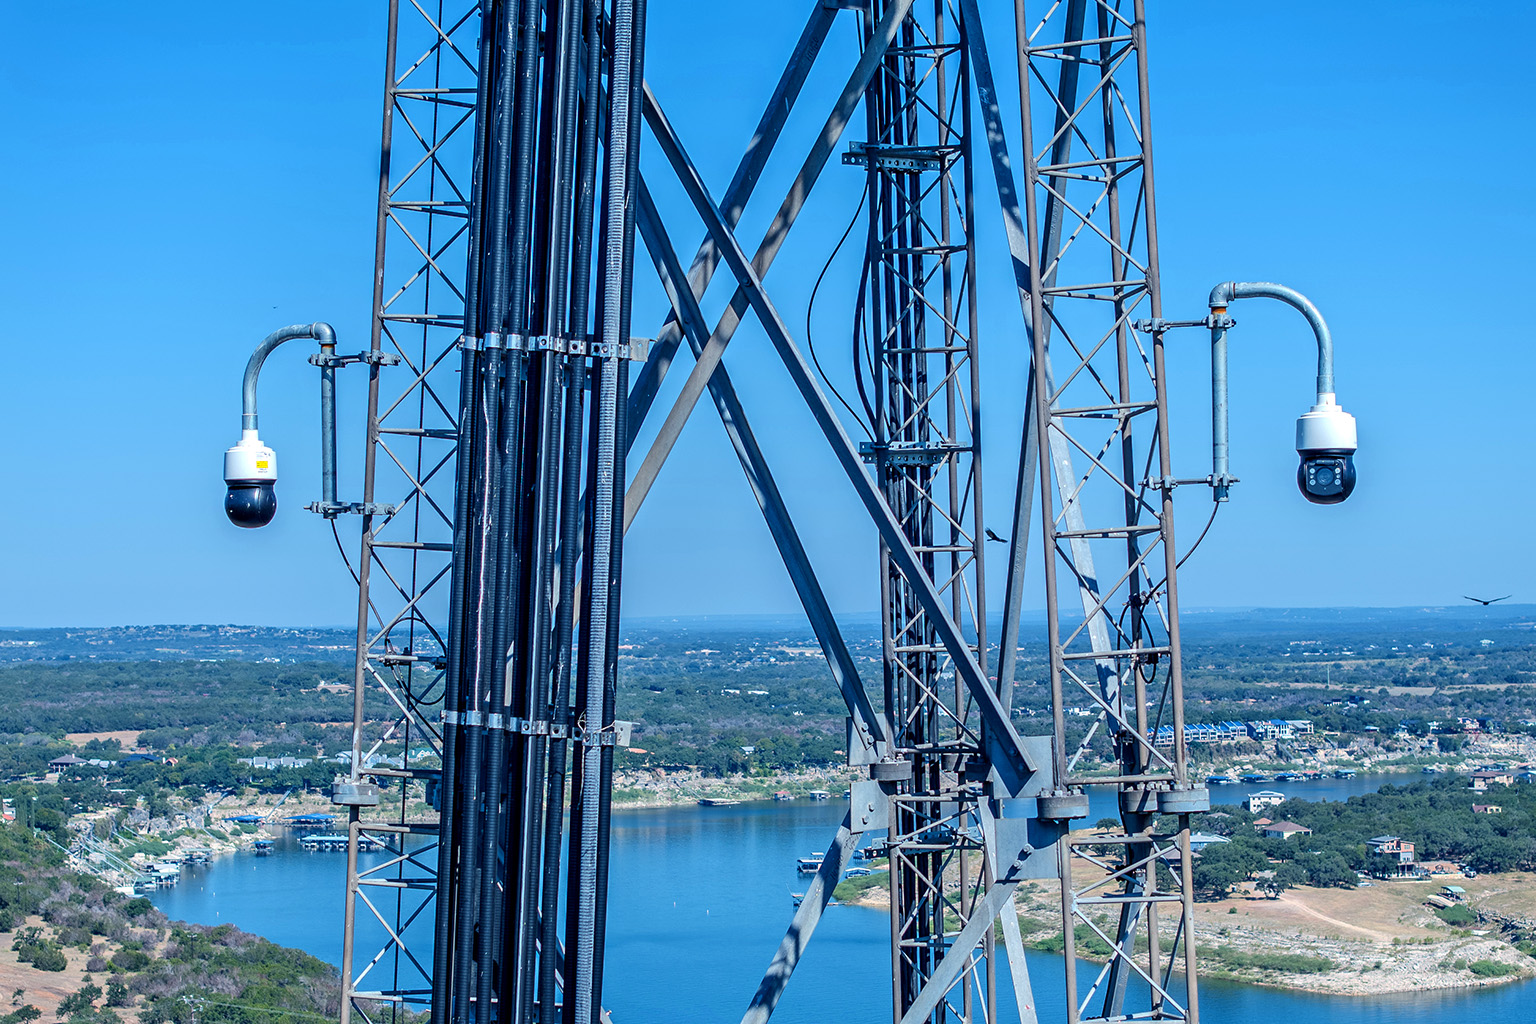
Case example 4: Wildfire detection, United States
Austin, Texas, is one of the most wildfire-exposed and fast-growing metropolitan areas in the United States. Austin Energy, the city’s publicly owned electric utility, sought to deploy an early-detection system in 2023 to spot wildfire ignition sooner.
Early-detection systems create value mainly through avoided losses. Because benefits are realized only when fires occur, the value of investing in detection was unclear at the outset of the project.
Austin Energy made that value more tangible through an in-depth technology evaluation and demonstrations to stakeholders in collaboration with emergency responders. The utility evaluated several emerging technologies, working alongside other Texas public utilities to understand their potential applications, before selecting Pano AI, a company that provides wild- and bushfire detection systems. It then worked with local fire departments to identify high-risk locations for camera placements and integrate automated alerts and real-time imagery into emergency-response workflows. Austin Energy then undertook pilots to demonstrate how earlier, more precise detection could help firefighters respond faster and limit potential losses, making the case for approval more concrete for the city councilors.
The system now combines cameras, AI detection, round-the-clock monitoring, and human verification to reduce false alarms. By 2024, Austin Energy had deployed 13 camera stations in its 437-square-mile service territory.49
Example actions for consideration
- Improving visibility into climate risks and benefits. Information campaigns, risk disclosures, pilots, and demonstration projects are among the approaches that can make climate exposure and the benefits of adaptation more tangible.
- Creating resilience standards and incentives. Hazard-aligned building codes and zoning regulations, for example, can enable decisions to proactively account for climate risks.
- Building resilience into investment decisions. Embedding adaptation into new infrastructure and other capital investments, along with using post-disaster reconstruction to repair or replace assets to a higher resilience standard, can often result in better outcomes than replacing assets to previous standards.
Enabling bankability becomes the priority when demand for adaptation broadly exists but projects cannot attract financing on acceptable terms. This is particularly relevant when projects lack predictable revenue streams, are too small to finance efficiently, or carry risks that capital providers are unwilling to bear.
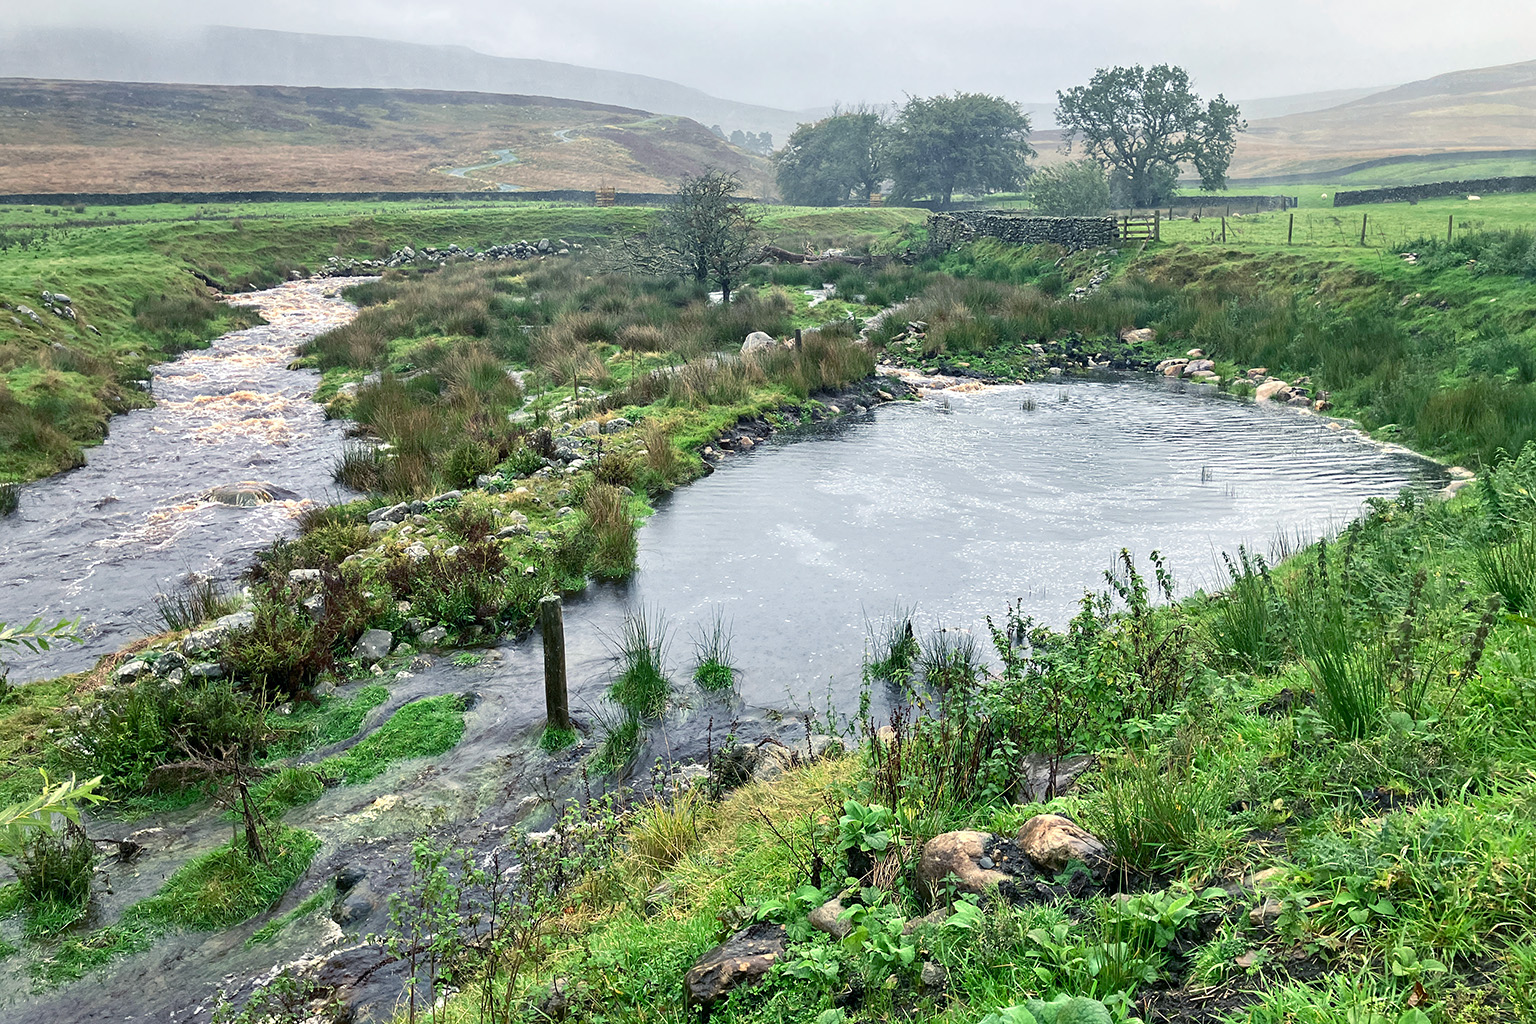
Case example 5: Wyre catchment natural flood management, United Kingdom
After repeated flooding in the Wyre River catchment in Lancashire, a group of public, private, and nonprofit partners began developing a natural flood management program in 2016. The program proposed more than 1,000 interventions on farmland, including planting woodlands and hedgerows, creating ponds, and installing small barriers designed to slow water flow and reduce downstream flood risk.
However, financing remained a challenge. The primary barrier was revenue risk. The proposed interventions would create value by reducing flood losses and delivering environmental benefits, which wouldn’t generate a predictable revenue stream against which investors could lend.
The project overcame that barrier by converting some benefits into contractual payments. Five beneficiaries, including insurers, utilities, and public agencies, agreed to make payments reflecting the benefits they expected to receive from the program. A dedicated community interest company secured roughly £2 million of payments, which supported a nine-year, £850,000 private loan. Together with a £627,500 grant, the loan covered about £1.5 million in up-front costs. The loan provided capital for the program, and beneficiary payments created the revenue stream needed to repay it.
Impact modeling estimated a 5 to 15 percent reduction in flood impacts, with some individual interventions potentially reducing peak flows by up to 20 percent. Ongoing monitoring will measure actual performance and help inform future beneficiary payments based on outcomes.50
Example actions for consideration
- Creating predictable revenue streams. Banks and companies can explore partnerships to develop new business and financing models that generate cash flow to support financing. Examples include contractual beneficiary payments, dedicated fees, subscription models, and repayment linked to future savings.
- Bundling assets to support repayment. Adaptation measures with benefits primarily from avoided losses can be combined with revenue-generating assets. For example, flood protection infrastructure could be bundled with a toll road or other infrastructure that generates revenue to help repay financing.
- Aggregating projects to create scale. Smaller investments pooled together can reduce transaction costs and make them more attractive to capital providers.
- Filling remaining financing gaps. Targeted use of public funds, for example, can help overcome risks or economics that prevent commercial capital from financing the full investment.
Proving feasibility is important when newer adaptation technologies lack a track record of reliable performance, creating uncertainty that can deter financing. This is particularly relevant for newer technologies that need to demonstrate performance in real-world conditions and at scale before capital providers are willing to invest.
Case example 6: Drought-tolerant maize for sub-Saharan Africa
Drought is a major threat to maize production across sub-Saharan Africa. In 2007, two nonprofits, the International Maize and Wheat Improvement Center and the International Institute of Tropical Agriculture launched the Drought Tolerant Maize for Africa initiative to develop and distribute maize varieties that could maintain higher yields during drought.
Finding funders willing to finance experimental agriculture like the development of drought-tolerant maize seeds was difficult. Developing new varieties requires years of R&D and field testing before sufficient evidence demonstrates reliable performance during drought as well as yield maintenance when rainfall is normal. This time- and capital-intensive process created technology risk that limited seed innovators’ access to traditional commercial capital. The initiative also faced an execution challenge because to prove the new seeds worked, the program needed to reach farmers across the region and build their capacity to produce and distribute the new seed varieties at scale.
Donors provided sustained grants for R&D and field testing, overcoming technology risk by allowing the new varieties to establish a performance record that would attract commercial lenders. To address the execution challenge, the nonprofits prioritized building seed-production capacity by training breeders and producers, accelerating varietal releases, and partnering with local seed companies and national research programs to improve long-term sustainability. By 2014, more than 90 small and midsize seed companies were stocking drought-tolerant varieties, and nearly 54,000 tons of certified seed had reached an estimated 5.4 million households, or 43 million people. This targeted additional grain is worth $160 million to $200 million annually in the drought-affected area.51
Example actions for consideration
- Testing solutions in real-world conditions. Pilots, field trials, and demonstration projects can establish performance and build evidence at increasing scale.
- Funding early-stage development. Grants and subsidies can support research, development, and testing before commercial capital is willing to take the risk.
- Diversifying technology risk across a portfolio. Combining newer technologies with more mature, proven solutions can reduce the impact of uncertainty in any single technology and make the overall investment risk profile more manageable.
- Tying funding to verified results. Results-based financing such as outcome bonds can link payments to demonstrated performance outcomes.
- Releasing capital as milestones are met. Progress-based payments provide funding as technologies achieve defined development and delivery milestones.
These case studies and example actions show how barriers to adaptation can be overcome at the local level. But local actors do not have to undertake these efforts alone. In some instances, global actions and platforms can support local efforts.
For example, risk transparency through better data on climate hazards, exposure, and the benefits of adaptation can help improve decision-making. Know-how can provide the technical, institutional, and delivery expertise needed to design, structure, and implement adaptation effectively. Common standards can reduce the cost and complexity of designing and replicating solutions in different locations. Capital mobilization can connect local adaptation opportunities with larger pools of finance, including by aggregating projects and developing common investment metrics.52
These actions do not replace locally tailored responses. Rather, they can make those responses more effective and accelerate deployment.
What does this mean for decision-makers?
For those seeking to invest in climate resilience, the patterns of response highlighted in the previous chapter can help inform how to best tackle barriers to adaptation. Companies, financial institutions, and public- and social-sector actors can use this understanding to consider how to strengthen their own resilience and support the resilience needs of others (Exhibit 11).
Stakeholders can use their understanding of barriers and responses to strengthen resilience and unlock opportunities in growing adaptation markets.
Corporations can build capabilities, partnerships, and innovative solutions for adaptation
The barriers identified in this research, including gaps in perceived benefits, competition from other investment priorities, and execution challenges, confront companies. To overcome them, companies can consider building capabilities to better value adaptation and partnerships to implement responses.
- Build the muscle to value adaptation. Developing tools and expertise within existing risk and capital-planning processes is one place to start. This helps quantify the costs of adaptation and its benefits in terms of avoided losses and other business benefits. With this understanding, decision-makers can more effectively identify potential actions and better assess adaptation against other investment needs, considering current and future climate hazards.
- Prioritize where and how best to embed adaptation. With a better understanding of the value of adaptation, companies can determine where dedicated adaptation investments meet the financial return thresholds that typically apply to other investments and the sequence for deploying pertinent measures. Resilience can also be embedded into planned projects because building it into the design and upgrading of assets can avoid expensive retrofits and extend asset lives. In some cases, investments that companies make for broader resilience beyond protecting against extreme weather events, like energy reliability or supply-chain resilience, can also strengthen climate resilience. In implementing measures, companies can also consider how to best account for uncertainty in future climate risks in their adaptation responses. Responses could range from implementing “no regrets” measures that deliver benefits under any scenario and carefully sequencing responses to establishing more conservative design standards for critical assets and flexible strategies with trigger points that signal when further investment is needed as conditions evolve.
- Consider building partnerships that could overcome coordination and capability challenges. Realizing the benefits of adaptation can depend on suppliers, distributors, communities, and infrastructure providers acting in tandem. Partnerships can align incentives and add capabilities that companies lack. In South Africa, Woolworths partnered with its fruit suppliers, a regional water authority, and the World Wide Fund for Nature to mitigate shared water risks because no single farm or company could secure its water supply and quality without coordinated resilience action across the catchment.53
Understanding demand and financing barriers also allows companies that are providers of resilience solutions to identify where clear demand for adaptation is likely to exist and the role they can play in supporting the resilience needs of others.
- Provide adaptation solutions and consider how to innovate to unlock demand. Some companies also have an important role to play in adaptation as solution providers. AiDASH, for example, uses satellite data and AI to help utilities manage vegetation, wildfires, storms, and other physical risks to infrastructure. In 2026, Schneider Electric agreed to acquire approximately 90 percent of the company for $350 million.54 However, solution providers may need to build skills to distinguish between near- and longer-term opportunities. Near-term markets may have demonstrated willingness to pay, for example, in the wake of recent extreme weather events or may have policies that trigger a demand response. Longer-term opportunities include markets where adaptation needs are growing but demand has yet to materialize at scale. Capturing these longer-term opportunities may require companies to continue to innovate to lower costs, demonstrate the value and feasibility of their solutions, and move from pilots to scalable projects.
Financial institutions can participate in growing adaptation markets and consider how to spur demand
Banks can identify and structure adaptation opportunities that fit their risk appetite.
- Support adaptation demand across existing relationships and products. Banks can identify the households and businesses they already serve where clear demand for adaptation already exists and use those established relationships to explore opportunities to provide financing. BMO offers discounted financing for qualifying climate-resilience investments, for example, to small and midsize businesses that floodproof buildings.55 Such measures can help strengthen the resilience of households and businesses and potentially improve the resilience of banks’ portfolios.
- Examine where and how to enable bankability. Where demand broadly exists but financing is constrained, banks can identify what’s needed to get capital to flow. This could involve innovative structuring and underwriting approaches like aggregating smaller investments and standardizing successful approaches to reduce transaction costs, making financing easier to scale.56
- Consider partnerships that could unleash novel revenue streams. Where demand exists, stakeholders including banks, implementers, beneficiaries, and insurers can come together to create revenue streams that could support financing for adaptation (see sidebar “Translating resilience benefits into predictable revenue streams”). This could include beneficiary payments, payments tied to future energy or insurance savings, and dedicated fees or subscription models that replace upfront payments with recurring fees.
- Build and share an evidence base from financed projects. Sharing data on how adaptation investments perform against expected physical risks and their resilience outcomes with implementers can make the benefits of adaptation more visible and potentially strengthen incentives to invest. Building a track record can also reduce uncertainty for financiers over time, helping inform underwriting and credit decisions.
Investors can consider how to advance adaptation in their portfolios and support emerging solutions.
- Evaluate how to strengthen the resilience of portfolio companies. Investors can identify where physical climate risks could materially affect portfolio companies and encourage resilience investments to manage those risks.
- Consider where private capital can close commercialization gaps in adaptation. When adaptation technologies are moving from early-stage innovation to commercial scale, investors can provide targeted risk capital to help establish commercially viable business models. CoolPact Capital, for example, is a dedicated investment vehicle designed to finance early-stage cooling companies in India.57
Insurers can use their expertise to strengthen resilience and manage residual risks
Insurers can advance adaptation by creating incentives for asset owners to reduce risk, collaborating with other stakeholders to support investments that protect multiple beneficiaries, and providing protection against residual risk.
- Determine whether insurance can play a role in encouraging resilience. Premiums and coverage signal underlying physical climate risk. Lower premiums for resilient assets are unlikely to be sufficient on their own, and combining them with more stable coverage and pricing as well as partnerships with banks on premium-linked financing could help strengthen incentives to invest in adaptation. In California, insurers have begun offering discounts on property insurance for homeowners who adopt wildfire adaptation measures, though it is too early to determine how popular those are.58
- Consider building partnerships with other insurers to support shared resilience. Measures such as levees, sea dikes, and watersheds manage flooding and protect whole communities. But they benefit multiple beneficiaries, making it difficult for any single insurer to justify the investment. Insurers can work together and with other stakeholders to aggregate beneficiaries, quantify avoided losses, and explore financing structures that could support investment in shared resilience. In the United Kingdom, for example, the FloodAction Coalition brings together insurers, investors, and landowners to cofinance natural flood management. At launch, it set a target to bring an initial £150 million pipeline of projects online in 2026 and build a £1 billion-plus resilience market by 2028.59
- Provide products and services to manage residual risk. When asset owners choose to bear some or all of a risk, they can use insurance to shift part of the financial burden through conventional policies or variations such as parametric insurance. Such products were launched for women farmers in India and construction workers in Hong Kong to help protect them from income loss during extreme heat.60
The public and social sectors can consider approaches to strengthen demand, delivery, and target capital
The public and social sectors can determine if and where to step in to create an environment that encourages demand for adaptation and supports its effective delivery, as well as deploy capital where adaptation offers clear benefits but affordability constraints and other barriers constrain investments. Given their finite resources and competing priorities, decision-makers will confront trade-offs and consider how to act strategically, for example by targeting support to places where affordability and financing constraints are greatest.
- Evaluate the role policy can play to create demand when market signals are insufficient. Some jurisdictions are embedding resilience standards in building codes, zoning, and procurement to make risks and benefits more visible.
- Examine opportunities to improve coordination. When willingness and ability to pay exist but execution is holding adaptation back, one approach is to establish dedicated teams with clear accountability to coordinate between agencies. Doing so can help resolve bottlenecks such as lengthy approvals and contracting delays that prevent projects from moving forward.
- Explore how to prioritize scarce public and development capital where it can have the greatest impact. Given scarce resources, prioritization is key to adaptation and other development priorities. One approach is to target support to populations and measures facing the greatest ability-to-pay constraints to help close affordability gaps. Focusing on measures with large benefit-to-cost ratios is another approach. Yet another is distinguishing investments that require public or concessional funding from those where targeted public support could mobilize additional private capital and stretch scarce resources further. The Green Climate Fund’s investment in the Acumen Resilient Agriculture Fund, for example, used its first-loss equity to reduce investment risk and attract other investors to agribusinesses, supporting climate resilience among smallholder farmers in Africa (see sidebar “How can blended finance advance adaptation?”).61
- Evaluate how to embed resilience into economic development. Integrating climate risk and resilience requirements from project appraisal through design and construction can often cost less than adapting assets later and can potentially improve project performance and useful life. Importantly, the presence or absence of adaptation may influence the pace of economic development.62
- Explore building a pipeline that investors can act on. Funding project preparation and working with sponsors to turn adaptation plans into well-structured projects could give investors visibility into upcoming opportunities and make it easier to develop financing approaches that can be replicated.63
Around the world, companies, capital providers, and public-sector actors have found ways to overcome barriers to adaptation through innovative financing, regulation, and incentives that better align costs and benefits. The examples in this report point to a way forward to address resiliency gaps and adaptation needs by illustrating how various parties have overcome barriers to protect people, assets, and operations, enhance resilience across value chains, and develop new solutions. Ultimately, households, governments, and companies choose where and how to invest in resilience. Understanding the barriers to adaptation and potential responses can help them make more informed decisions and turn the world’s adaptation needs into effective action.
Related Articles
Advancing adaptation: Mapping costs from cooling to coastal defenses
Advancing adaptation: How evolving hazards could shape the agenda