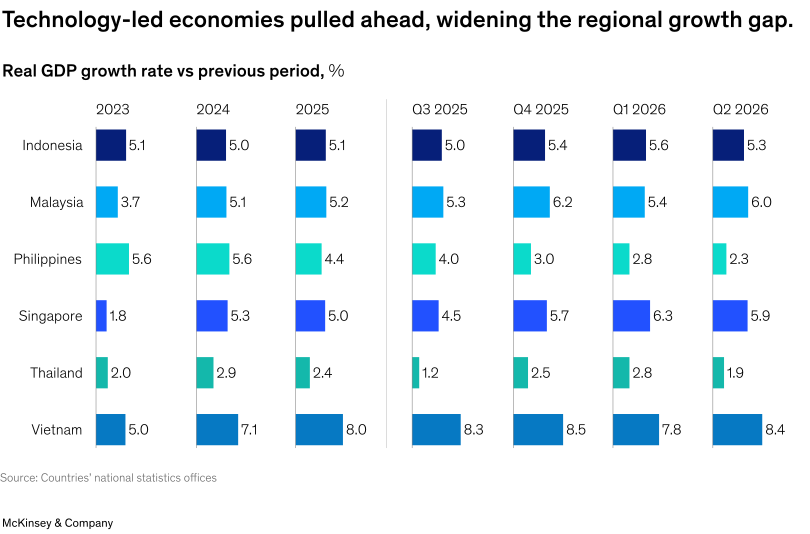
After a strong start to 2026, Southeast Asia shifted to two speeds in the second quarter, with technology and trade-led economies pulling ahead while softer domestic activity tempered growth elsewhere. Vietnam and Malaysia accelerated to 8.39 percent and 6.0 percent, respectively, while Singapore remained robust at 5.9 percent and Indonesia sustained its momentum with 5.29 percent expansion, forming the stronger-growth group. In contrast, Thailand and the Philippines lost momentum, with growth moderating to 1.9 percent and 2.3 percent, respectively, amid softer domestic activity (Exhibit 1).1
Exports were the region’s standout growth engine, as global demand for electrical and electronics (E&E) and other technology-related output supported trade across all six markets. Industrial activity strengthened in Malaysia, the Philippines, Singapore, and Vietnam, while Indonesia and Thailand were softer, although July Purchasing Managers’ Indexes (PMIs) pointed to improving factory conditions entering the third quarter. Private consumption remained supportive but moderated in several markets amid higher living costs, while foreign investment remained broadly resilient, anchored by technology, manufacturing, and digital infrastructure.
Meanwhile, the Middle East energy shock is increasingly feeding through inflation, currencies, and monetary policy. Inflation accelerated in five of the six economies, most sharply in the Philippines and Vietnam, while currency pressures were concentrated in the Indonesian rupiah, Philippine peso, and Thai baht. Policy responses consequently varied: Indonesia and the Philippines tightened monetary policy and Singapore tightened its exchange-rate policy, while Malaysia, Thailand, and Vietnam maintained their existing settings.
Looking ahead, technology-led exports and improving manufacturing indicators provide a strong platform entering the second half, but the durability of regional growth will also depend on how inflation, currency pressures, and household demand evolve. The second quarter therefore leaves Southeast Asia with a more differentiated growth picture: a powerful external technology cycle continues to provide momentum, while the energy shock is testing how effectively individual economies can translate that tailwind into broader domestic growth.
Regional economic overview
In this article, we focus on the economies of six countries in Southeast Asia: Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam. We start by setting the scene with a regional overview (Exhibit 2).
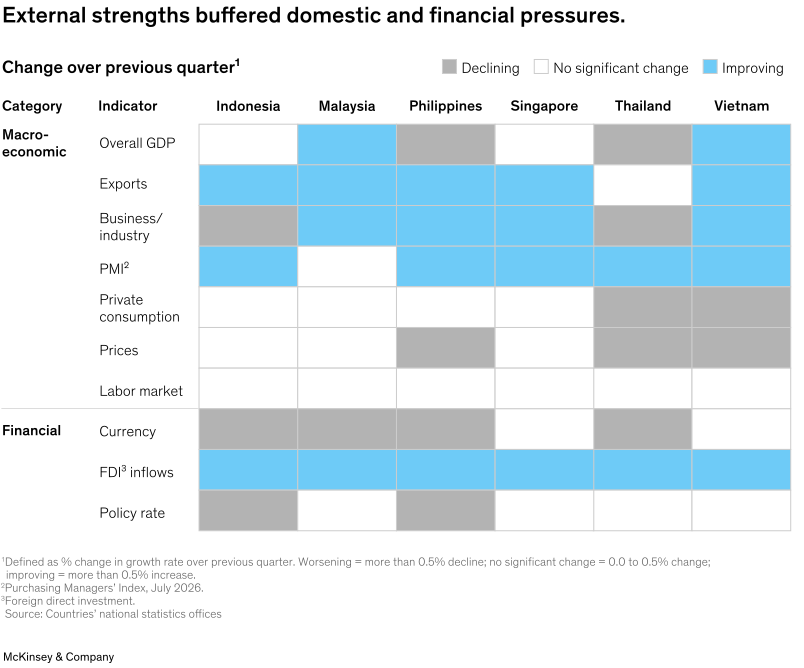
In the following section, we focus on these six countries in Southeast Asia, examining their macroeconomic conditions and financial markets.
Indonesia
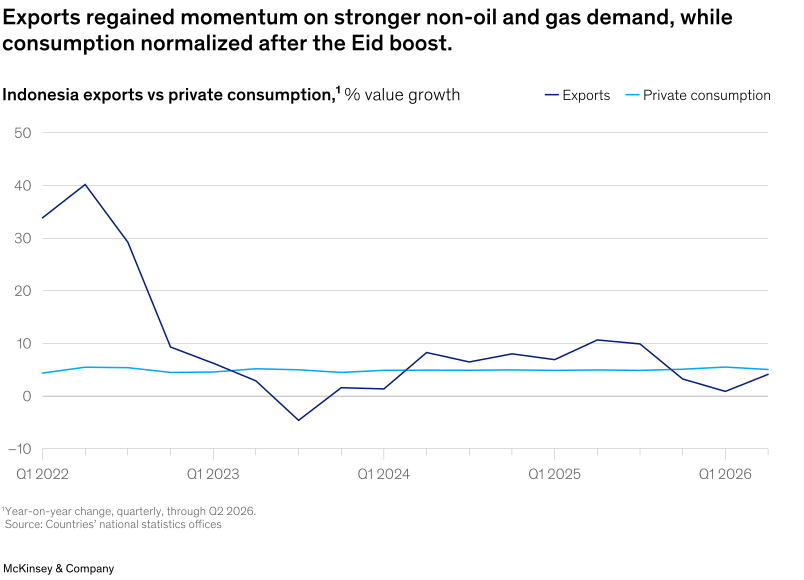
Following a robust first quarter, Indonesia’s economic momentum moderated in the second quarter of 2026 as domestic demand normalized and external headwinds intensified. GDP growth eased from 5.61 percent in the first quarter to 5.29 percent in the second quarter, while Bank Indonesia raised its benchmark policy rate by a cumulative 100 basis points to stabilize the rupiah amid heightened market volatility. On the demand side, household consumption moderated as the seasonal festive boost faded, although export growth rebounded (Exhibit 3). Manufacturing activity also softened, while foreign direct investment remained a bright spot, recording its strongest growth since the fourth quarter of 2024.
Despite softer second-quarter momentum, Bank Indonesia maintained its growth forecast of 4.9 to 5.7 percent for 2026. External analysts remain cautious and expect growth to moderate further as tighter monetary policy and persistent external headwinds weigh on domestic activity. Against this backdrop, policymakers could face the challenge of supporting economic growth while safeguarding macro-financial stability amid risks of renewed capital outflows and continued pressure on the rupiah.2
Macroeconomic outlook
GDP: Indonesia’s economy expanded by 5.29 percent in the second quarter of 2026, moderating from 5.61 percent in the previous quarter as the seasonal boost from Ramadan and Eid faded. Growth remained broad based, with manufacturing the largest contributor, while trade, construction, and information and communication also recorded solid gains; mining was the only sector to contract. On the expenditure side, all major components expanded, led by a surge in government consumption, while household consumption remained the largest contributor to GDP growth despite moderating. Although exports rebounded, imports grew more rapidly, weighing on net exports.3
Private consumption: Household consumption, which accounts for just over half of Indonesia’s GDP, moderated to 5.06 percent in the second quarter of 2026 from 5.52 percent in the previous quarter. The slower pace reflected the absence of the seasonal boost from Ramadan and Eid festivities that had previously driven first-quarter consumption growth to its fastest rate since 2022.4
Trade: Indonesia’s export growth strengthened to 4.13 percent in the second quarter of 2026 from 0.90 percent in the previous quarter, marking the first acceleration after two consecutive quarters of slowing growth. The recovery was driven by stronger non-oil and gas exports across the commodity and manufacturing sectors.5
Industrial activity: Manufacturing output growth moderated for a third consecutive quarter, easing to 4.52 percent in the second quarter of 2026 from 5.04 percent in the previous quarter.6 The slowdown was also reflected in business sentiment, with Indonesia’s Manufacturing PMI falling further to 46.9 in June, from 50.1 at the end of the prior quarter, as weaker domestic and export demand weighed on new orders, output, and employment.7 Manufacturing conditions began to show early signs of recovery at the start of the third quarter, with the PMI rebounding to 50.2 in July as production returned to growth, new orders stabilized, and firms resumed hiring, although the recovery remained modest amid lingering demand uncertainty.8
Labor: Indonesia’s unemployment rate edged down to 4.65 percent in May 2026 from 4.68 percent in February.9 However, the modest improvement masked persistent structural weaknesses, as formal job creation continued to lag labor force growth and a large share of workers remained in informal employment. Rising unemployment benefit claims and longer job search periods also point to ongoing challenges in securing stable, quality employment despite the lower headline unemployment rate. These trends underscore the importance of expanding formal-sector employment opportunities to support more inclusive labor market outcomes.10
Inflation: Inflationary pressures eased in the second quarter of 2026, with annual inflation moderating from 3.48 percent at the end of the first quarter to 3.34 percent in June before falling further to a three-month low of 2.88 percent in July. The decline was driven by easing food prices and improved domestic supply conditions, which helped offset inflationary pressures from higher global oil prices. With inflation remaining comfortably within Bank Indonesia’s 1.5 to 3.5 percent target range throughout 2026, the central bank was able to pause its tightening cycle in July while maintaining its focus on exchange rate stability.11
Financial markets
Currency: The Indonesian rupiah came under significant pressure during the second quarter of 2026, breaching the key psychological level of Rp18,000 per US dollar and depreciating by around 8 percent year-to-date as of June, making it one of Asia’s weakest-performing currencies. The sell-off reflected stronger safe-haven demand for the US dollar amid heightened geopolitical tensions, higher oil prices, and investor concerns over Indonesia’s fiscal and policy outlook.12 In response, Bank Indonesia raised its policy rate by a cumulative 100 basis points in May and June, helping to stabilize the rupiah. The central bank held rates in July and introduced complementary measures to attract capital inflows and support the currency.13
Policy rate: Bank Indonesia implemented an aggressive monetary tightening cycle in the second quarter, raising its benchmark policy rate by a cumulative 100 basis points to stabilize the rupiah and curb capital outflows.14 In July, as inflationary pressures started to ease, the central bank kept its benchmark rate unchanged at 5.75 percent, signaling a shift toward targeted macroprudential and liquidity measures, with the central bank introducing incentives to attract foreign portfolio inflows and support domestic credit growth while continuing to safeguard exchange rate stability.15
Capital flows: FDI into Indonesia accelerated for a third consecutive quarter, rising 27.4 percent year-on-year to Rp257.7 trillion ($14.3 billion) in the second quarter of 2026, which also marked the strongest growth since the fourth quarter of 2024. China, Hong Kong, Japan, and Singapore remained the country’s largest sources of FDI, while base metals and mining continued to attract the largest share of investment, reflecting Indonesia’s ongoing downstream industrialization strategy.16
Malaysia
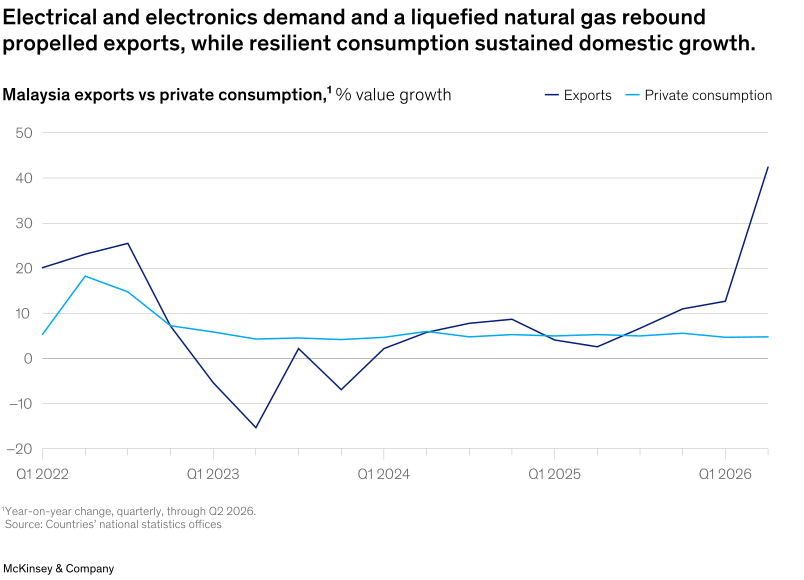
Malaysia’s economy expanded at a faster pace in the second quarter of 2026, with GDP growth accelerating to 6.0 percent from 5.4 percent in the first quarter. Strong export growth, steady household consumption, and sustained investment, particularly in technology and AI-related infrastructure, helped cushion the economy from disruptions arising from the ongoing Middle East conflict (Exhibit 4). Labor market conditions remained resilient, while inflation edged higher but underlying price pressures remained relatively contained.
Malaysia’s growth outlook remains positive, with the economy projected to expand by 4.0 to 5.0 percent in 2026, although Bank Negara Malaysia sees scope for growth to reach the upper end of the range or potentially slightly higher following the stronger-than-expected second-quarter performance. Firm exports and continued technology investment are expected to underpin growth, while easing supply disruptions could provide further support.17
Macroeconomic outlook
GDP: Malaysia’s GDP growth accelerated to 6.0 percent year-on-year in the second quarter of 2026, from 5.4 percent in the first quarter. Growth in the services sector, the economy’s primary driver, strengthened on robust business-related activities, particularly information and communication technology (ICT) amid sustained data center demand, as well as finance and insurance, while manufacturing gained momentum on strong demand for AI- and data center-related E&E components. Mining also rebounded on higher natural gas production, while construction growth moderated and agriculture contracted as oil palm yields normalized.18
Private consumption: Private consumption continued to anchor Malaysia’s economic growth, edging up to 4.8 percent in the second quarter from 4.7 percent in the first, supported by resilient labor market conditions, steady income growth, and policy measures.19 Household spending is expected to remain resilient in the second half of 2026, underpinned by low unemployment, rising wages, and contained inflation. However, momentum could moderate as higher food and living costs weigh on purchasing power and festive spending fades, partly offset by continued government support.20
Trade: Malaysia’s trade activity strengthened considerably in the second quarter, with export growth surging to 42.4 percent from 12.7 percent in the first quarter, driven by strong E&E exports alongside a rebound in liquefied natural gas and non-E&E manufactured products. Import growth similarly accelerated to 25.4 percent from 7.7 percent, supported by robust demand for intermediate goods.21
Industrial activity: Malaysia’s manufacturing sector gained momentum in the second quarter, with output growth accelerating to 7.3 percent from 5.9 percent in the first quarter. The expansion was driven by export-oriented industries, particularly in E&E, supported by robust AI-related demand.22 Forward-looking indicators point to stable manufacturing momentum, with the PMI holding at 50.7 in July, slightly below April’s four-year high of 51.6, but remaining in expansionary territory. Growth was supported by new orders rising at their fastest pace in eight months and a renewed increase in export demand, while cost pressures eased to a five-month low. Business confidence and employment remained soft, as subdued market conditions and ongoing geopolitical tensions weighed on manufacturers’ expectations.23
Labor: Malaysia’s labor market remained resilient in the second quarter, despite the unemployment rate edging up to 3.0 percent from 2.9 percent in the first quarter, while employment continued to expand amid steady labor demand. Employment gains were broad-based across most economic sectors, with services remaining the country’s largest source of employment.24
Inflation: Headline inflation rose further to 1.9 percent in the second quarter, from 1.6 percent in the first quarter, mainly reflecting the economic impact of the Middle East conflict, which pushed up global energy prices and domestic fuel costs. Higher transport and electricity costs contributed to the increase, although underlying price pressures remained relatively contained. Looking ahead, inflation is projected to average 1.5 to 2.5 percent in 2026, with policy measures helping to cushion external cost pressures, although global energy and commodity prices remain a key upside risk.25
Financial markets
Currency: Following a resilient first quarter, when the Malaysian ringgit appreciated by 0.5 percent, the currency depreciated by 0.8 percent in the second quarter, weakening past the psychologically important RM4 per US dollar level in June and reaching its lowest level since November 2025. The depreciation largely reflected a more hawkish US Federal Reserve outlook, as markets increasingly expected US interest rates to remain higher for longer, strengthening the US dollar and reducing investor appetite for regional currencies. Despite Malaysia’s resilient economic fundamentals and strong foreign bond inflows, these external pressures dominated currency movements during the quarter.26
Policy rate: Bank Negara Malaysia maintained its policy rate at 2.75 percent at its policy meetings in May and July 2026, extending a year-long pause to balance resilient domestic economic growth against moderate inflationary pressures. The central bank anticipates that inflation will remain contained despite upside risks from elevated global commodity prices and the ongoing Middle East conflict, signaling a continued steady monetary policy outlook for the near term.27
Capital flows: Malaysia recorded RM7.4 billion ($1.8 billion) in FDI inflows in the second quarter, representing a steady 8.8 percent year-on-year increase. Inflows were concentrated in the services sector, particularly ICT and professional and technical activities, with China, Hong Kong, and Singapore among the key sources of investment, reflecting Malaysia’s broader efforts to attract higher-quality investments and move up the value chain. While such investments could eventually contribute to higher wages and household incomes, their benefits are likely to take time to flow through to the wider economy.28
The Philippines
The Philippine economy grew by 2.3 percent in the second quarter of 2026, its slowest pace since 2021, as elevated inflation from the Middle East energy shock eroded purchasing power, while the lingering effects of last year’s graft scandal and delayed budget implementation continued to constrain public spending and investment. These headwinds offset an early recovery in manufacturing and stronger exports, supported by robust global demand for electrical and electronic products (Exhibit 5). With inflationary pressures remaining elevated and the Philippine peso near record lows, Bangko Sentral ng Pilipinas raised its policy rate by a cumulative 50 basis points during the quarter, reversing the easing that had supported growth in prior quarters.
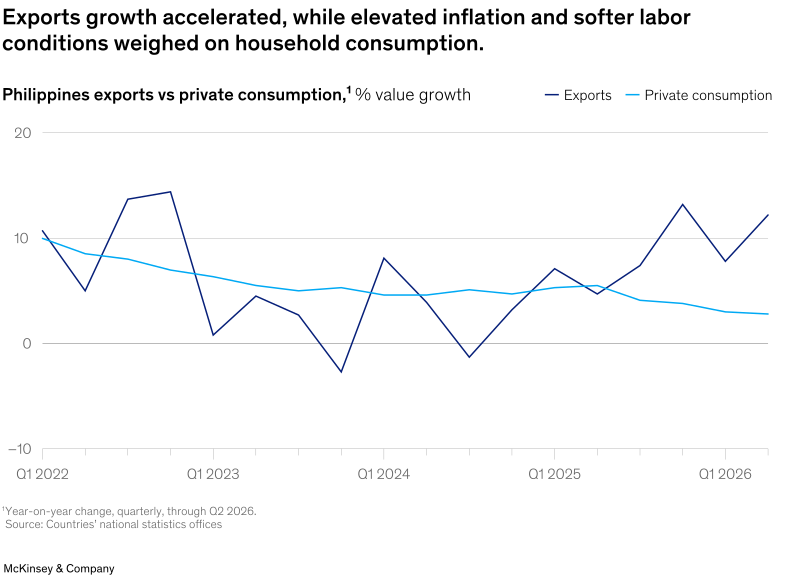
The second quarter performance brought the Philippines’ average growth in the first half of 2026 to 2.6 percent, well below the government’s recently revised full-year target of 3.5 to 4.5 percent. Looking ahead, an expected pickup in infrastructure spending and improving production and business confidence indicators could offer tentative signs that economic activity is beginning to recover in the near term.29
Macroeconomic outlook
GDP: GDP growth slowed to 2.3 percent in the second quarter of 2026 from 2.8 percent in the previous quarter, marking the country’s weakest quarterly performance in five years. The slowdown reflected persistent domestic headwinds, with elevated inflation weighing on household consumption and subdued public infrastructure spending constraining activity.
From a sector perspective, the services sector, which accounts for about two-thirds of GDP, recorded a fourth consecutive quarter of growth moderation to 4.5 percent, while the industry sector contracted by 2.4 percent, dragged down by a 13.9 percent slump in construction and continued weakness in mining. Manufacturing was a notable bright spot, with growth accelerating to 2.6 percent from 0.1 percent in the previous quarter, while agriculture, forestry, and fishing rebounded by 2.7 percent after two consecutive quarters of contraction, supported by improved commodity output, particularly rice.30
Private consumption: Household consumption, which accounts for more than two-thirds of the Philippine economy, slowed further to 2.8 percent in the second quarter of 2026 from 3.0 percent in the previous quarter, marking a fourth consecutive quarter of moderation. Elevated inflation continued to erode purchasing power, while concerns over employment and income prospects weighed on consumer confidence and household spending.31
Trade: Export growth accelerated to 12.2 percent in the second quarter of 2026 from 7.8 percent in the previous quarter, marking one of its strongest performances in the past three years. Goods exports expanded by 17.0 percent, up from 13.3 percent, supported by strong shipments of consumer electronics, semiconductors, machinery, transport, and office equipment. Services exports also strengthened, with growth accelerating to 6.9 percent from 3.0 percent in the first quarter.32
Industrial activity: Manufacturing growth accelerated to 2.6 percent in the second quarter of 2026 from 0.5 percent in the previous quarter, led by a 15.5 percent output growth in computers, electronics, and optical products, alongside gains in refined petroleum, food products, and basic metals. Manufacturing PMI edged up to 51.8 in July, marking a third consecutive month of expansion as new orders and output improved to pre-Middle East conflict levels. However, higher energy and shipping costs intensified cost pressures, while subdued business confidence kept firms cautious about hiring.34
Labor: Labor market conditions softened toward the end of the second quarter, with unemployment rising to a three-month high of 4.9 percent in June as new graduates and other workers entered the labor force, although the rate remained slightly below the 5.0 percent recorded at the end of the first quarter. Job creation struggled to keep pace with the expanding labor supply, particularly among younger workers, highlighting persistent challenges in generating quality employment. Analysts cautioned that softer labor conditions could weigh on household spending and keep overseas employment an important outlet for excess labor.35
Inflation: Inflation surged to a three-year high of 7.2 percent in April and averaged 6.8 percent in the second quarter, up sharply from 2.8 percent in the first quarter, driven by higher transport, energy, and food prices. While headline inflation has since begun to ease, underlying pressures remain elevated amid sticky core inflation, rising labor costs, and geopolitical uncertainty, keeping further monetary tightening on the table as the central bank seeks to steer inflation back toward its 3 percent target.36
Financial markets
Currency: The Philippine peso depreciated by 2.2 percent against the US dollar in the second quarter of 2026, following a 3.0 percent decline in the previous quarter, before testing fresh record lows in late July. The peso is among Asia’s weakest-performing currencies, weighed down by Middle East tensions, higher global oil prices, and broad US dollar strength, with the Philippines’ dependence on energy imports adding to inflation and trade-balance concerns. The Bangko Sentral ng Pilipinas has intervened to curb excessive volatility, although persistent geopolitical and oil-price pressures continue to cloud the currency outlook.37
Policy rate: The Bangko Sentral ng Pilipinas reversed its easing cycle in the second quarter of 2026, raising its policy rate by 25 basis points in both April and June as higher global oil and fertilizer prices intensified food and fuel inflation and core price pressures broadened. The central bank now expects inflation to breach its 4.0 percent tolerance ceiling in both 2026 and 2027 before easing toward its 3.0 percent target in 2028 and has signaled its readiness to tighten its policy rate further if needed.38
Capital inflows: Foreign investment approvals in the Philippines surged 68.2 percent year-on-year to PHP115.2 billion ($1.87 billion) in the second quarter, marking the highest quarterly level since the third quarter of 2024. The Netherlands accounted for the largest share of commitments, followed by Germany and Singapore, while manufacturing dominated investment allocations at 68.4 percent, with utilities and mining and quarrying trailing behind. The headline increase was, however, underpinned by several sizable projects, suggesting that the improvement in investment commitments was relatively concentrated rather than broad-based.39
Singapore
Singapore’s economy remained robust in the second quarter, expanding by 5.9 percent year-on-year following 6.3 percent growth in the first quarter, bringing first-half growth to a stronger than expected 6.1 percent. Growth was broad-based, led by manufacturing, wholesale trade, and finance and insurance, with Singapore benefiting particularly from robust global AI-related demand, which propelled non-oil exports and manufacturing output to their strongest levels in five years (Exhibit 6). Against this backdrop, the Monetary Authority of Singapore (MAS) shifted toward a tighter monetary policy stance in April 2026, its first tightening since 2022, and tightened again in July, seeking to contain cost pressures stemming from the Middle East conflict while preserving support for economic growth.
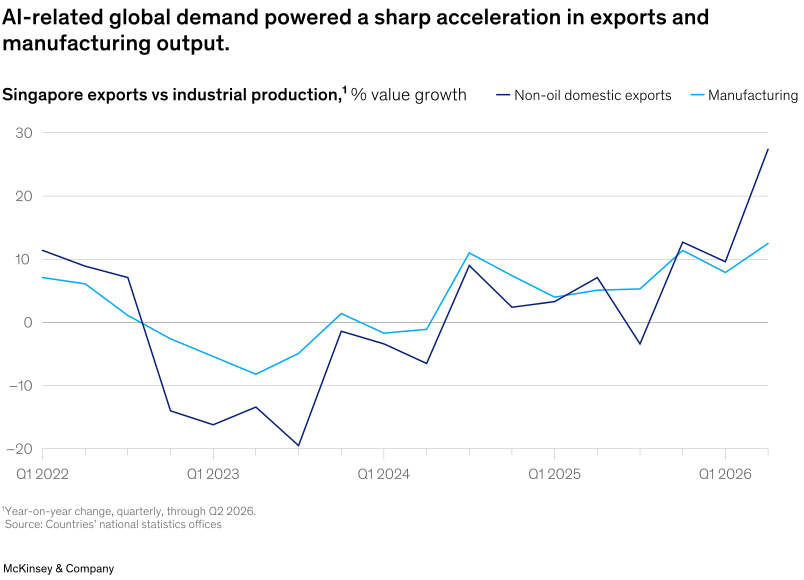
Looking ahead, the government raised its 2026 GDP growth forecast to 4.5–5.5 percent from 2–4 percent, following the stronger-than-expected first-half performance. The upgrade reflects continued strength in global AI-related investment, which is expected to sustain demand for Singapore’s electronics, semiconductor, and precision engineering industries, alongside a less severe economic impact from the Middle East conflict than initially anticipated. Nevertheless, the outlook remains subject to uncertainty from geopolitical developments and the durability of the global AI investment cycle.40
Macroeconomic outlook
GDP: Singapore’s economy expanded by 5.9 percent year-on-year in the second quarter, moderating from 6.3 percent in the previous quarter but remaining comfortably above forecasts. Growth remained broad-based, with manufacturing, wholesale trade, and finance and insurance among the key contributors.
Across major sectors, manufacturing gained further momentum, accelerating to 12.5 percent from 7.3 percent, supported by strong demand for AI-related electronics and precision engineering clusters. Services growth moderated to 4.9 percent from 6.3 percent, with all segments expanding except food and beverage services, while construction growth slowed to 5.8 percent from 12.9 percent despite continued increases in both public and private sector construction output.41
Private consumption: Following a moderation in the previous quarter, private consumption growth stabilized and edged up to 3.5 percent in the second quarter from 3.3 percent in the first. Household spending remained resilient, supported by broadly stable employment conditions.42
Trade: Singapore’s trade performance strengthened across the board in the second quarter, with all trade segments recording growth above 20 percent. Total merchandise trade growth accelerated to 40.2 percent from 25.6 percent in the first quarter, while non-oil domestic exports surged to 27.4 percent from 9.6 percent. Robust AI-related demand for electronics, particularly integrated circuits and disk media products, drove the expansion and lifted first-half non-oil domestic export growth to its fastest pace since 2010. Non-electronics exports also gained momentum, led by specialized machinery and pharmaceuticals, broadening the export expansion beyond electronics.43
Industrial activity: Manufacturing output accelerated to 12.5 percent in the second quarter from 7.3 percent in the first quarter, driven by strong AI-related electronics demand, which lifted electronics output by 33.8 percent, alongside robust growth in precision engineering. Performance remained uneven, however, with chemicals output continuing to contract amid supply-chain disruptions, while biomedical manufacturing declined by 17.3 percent on softer global demand and lower production.44 The PMI remained firmly in expansionary territory, rising to 59.2 in July 2026 from 57.9 in April, signaling sustained momentum in private sector activity. Growth was underpinned by robust new business and output, although supply constraints and elevated cost pressures continued to pose headwinds.45
Labor: Singapore’s unemployment rate remained unchanged at 2.0 percent in the second quarter, although retrenchments rose to 4,500 from 3,830 in the first quarter, the highest level since 2020, driven mainly by business restructuring in the services sector.46 Looking ahead, hiring is expected to remain cautious and uneven as AI continues to reshape the labor market, although employment is expected to be supported by domestic-oriented and modern services, with demand remaining strong for skilled technology and engineering roles.47
Inflation: Inflation continued its upward trajectory, albeit at a contained pace, rising to 1.8 percent in the second quarter from 1.5 percent in the previous quarter. Price increases were broad-based, led by higher transport costs amid rising car and petrol prices and public transport fares, partly offset by softer inflation in education and information and communications.48 Inflationary pressures are expected to remain elevated in the coming quarters as higher energy prices and supply-chain disruptions from the Middle East conflict feed into import costs, with MAS maintaining its 2026 inflation forecast at 1.5–2.5 percent, following an upward revision from 1.0–2.0 percent in the previous quarter.49
Financial markets
Currency: The Singapore dollar remained firm against the US dollar in the second quarter, trading within a narrow range and ending the quarter broadly unchanged, extending the trend from the first quarter. The currency subsequently strengthened by 1.2 percent across July and August and is expected to appreciate further in the second half of 2026, supported by MAS’ tighter monetary policy stance, resilient domestic growth and limited upside for the US dollar.50
Policy rate: MAS shifted toward a tighter monetary policy stance in April 2026, its first such move since 2022, to mitigate imported inflation from higher energy prices following the Middle East conflict. MAS tightened again in July, though by a smaller degree, as external cost pressures persisted and stronger-than-expected economic activity raised the risk of more persistent inflation. The measured back-to-back tightening reflects MAS’ focus on containing inflation while preserving support for economic growth amid continued global uncertainty.51
Capital inflows: Singapore recorded net FDI inflows of 58.6 billion Singapore dollars ($45.8 billion) in the second quarter, a slight increase from the 55.7 billion Singapore dollars registered in the previous quarter. On a year-on-year basis, this represented a 1.7 percent expansion, though it marked a moderation from the 12.1 percent expansion in the first quarter of 2026.52 Despite the moderation, Singapore remains a highly attractive destination for capital, serving as a stable regional refuge and growth hub with strong governance and strategic access to broader Southeast Asian opportunities.53
Thailand
Thailand’s economy lost some momentum in the second quarter, as softer private consumption and a decline in public investment weighed on activity, although stronger private investment provided some offset. GDP growth moderated to 1.9 percent from 2.8 percent in the first quarter, while the E&E segment remained a bright spot, supporting both export performance and manufacturing output (Exhibit 7). Inflation returned to positive territory after four consecutive quarters of decline, while the Thai baht continued to depreciate and the central bank maintained an accommodative policy stance, balancing support for growth against inflationary pressures
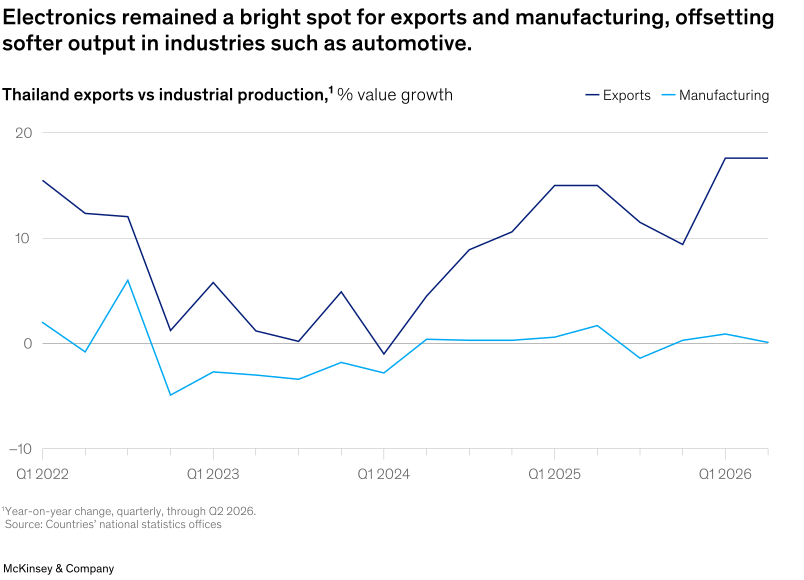
The second-quarter moderation brought first-half GDP growth to 2.4 percent, following which the government narrowed and raised the lower end of its 2026 growth forecast to 2.0–2.5 percent from 1.5–2.5 percent previously. Growth is expected to be supported by steady private consumption, robust exports, rising private investment, and government spending.54
Macroeconomic outlook
GDP: Thailand’s economic growth moderated to 1.9 percent year-on-year in the second quarter, from 2.8 percent in the first quarter, as activity slowed across most major sectors amid higher energy costs and disruptions from the Middle East conflict. Manufacturing growth eased amid weaker automotive and other key industrial output, while agriculture, construction, wholesale and retail trade, and tourism-related services also lost momentum, with the latter affected by a decline in international tourist arrivals. Nevertheless, the economy continued to draw support from robust exports, particularly technology-related products, and higher tourism receipts despite fewer foreign visitors.55
Private consumption: Private consumption continued to expand in the second quarter, albeit at a slower pace of 1.9 percent compared with 3.3 percent in the previous quarter, as higher living costs tempered household spending despite some support from government measures introduced in June. Spending remained positive across most categories, including food and beverages, vehicles, clothing, and footwear, although growth in services and fuel consumption softened. Consumer confidence eased to 50.3 from 52.8, its lowest level in 14 quarters, pointing to continued caution among households.56
Trade: Export growth remained robust at 17.6 percent in the second quarter, matching the pace recorded in the first quarter, supported by strong manufacturing exports, particularly electronics, amid sustained global demand. Agricultural exports also rebounded on higher global commodity prices, while telecommunications equipment, computer parts, and machinery recorded particularly strong growth; in contrast, passenger car exports contracted sharply. Exports to major markets including ASEAN-5,57 the European Union, and the United States continued to expand, while shipments to CLMV (Cambodia, Laos, Myanmar, Vietnam) countries, Hong Kong, and the Middle East declined.58
Industrial activity: The manufacturing sector lost momentum in the second quarter, with growth slowing to 0.1 percent from 0.9 percent in the previous quarter, alongside lower capacity utilization. The moderation reflected weaker production of key products, particularly motor vehicles, jewelry, and plastics and synthetic rubber, although gains in computers, processed food products, and selected domestic-oriented industries provided some offset. Forward-looking indicators, however, point to an improvement entering the third quarter, with July’s PMI rising to 54.2, its highest level in 2026, as new orders and production accelerated. Business confidence also continued to recover, supported by improving sales and expectations of expanded demand and products.59
Labor: Thailand’s unemployment rate edged up to 0.96 percent in the second quarter from 0.94 percent in the first, remaining at a relatively low level despite some signs of softer labor market conditions, including rising underemployment and declining working hours. Wage growth also remained subdued, with real wages below pre-pandemic levels, while gradual recovery in domestic demand and business conditions will remain important for supporting employment and household incomes.60
Inflation: Headline inflation rose to 2.7 percent in the second quarter from –0.5 percent in the first, mainly reflecting higher energy and food prices following the Middle East conflict and ending four consecutive quarters of negative inflation. Looking ahead, expectations of easing tensions in the Middle East and lower energy prices have prompted a downward revision to the inflation forecast to 1.5–2.0 percent, from 2.0–3.0 percent earlier in the year.61
Financial markets
Currency: The Thai baht depreciated by a further 2.0 percent against the US dollar in the second quarter, following a 4.2 percent decline in the first quarter, making it one of Asia’s worst-performing currencies since the onset of the Middle East conflict. The weakness largely reflected higher oil prices, which increased Thailand’s energy import bill and weighed on its trade and current account balances, alongside elevated US yields and Thailand’s relatively low interest rates. The baht weakened further in July before rebounding in August, although the rally may prove short-lived as elevated oil prices, a dovish Bank of Thailand and potentially wider interest-rate differentials with the United States continue to weigh on the currency.62
Policy rate: The Bank of Thailand kept its policy rate unchanged at 1.0 percent at both its April and June meetings, maintaining an accommodative stance after February’s 25-basis-point cut brought rates to a multiyear low. The decision to hold reflected policymakers’ assessment that the prevailing rate remained appropriate to support the economy, with higher inflation in April viewed as largely supply-driven and inflationary pressures expected to ease thereafter in June as supply-side pressures subsided. Looking ahead, the central bank will continue to monitor inflation and medium-term inflation expectations, with its next policy meeting scheduled for late August 2026.63
Capital inflows: Thailand sustained its strong FDI momentum in the second quarter, with first-half FDI applications surging 80 percent year-on-year to 1.37 trillion baht ($40.5 billion), accounting for the bulk of overall investment applications. Investment remained heavily concentrated in digital infrastructure and AI-related projects, particularly data centers and cloud services, with Singapore emerging as the largest source of FDI, followed by the United Kingdom, China, Taiwan, and Japan.64
Vietnam
Vietnam’s economy expanded by 8.39 percent year-on-year in the second quarter of 2026, accelerating from 7.8 percent in the previous quarter. Growth was broad-based, with industry, construction, and services all posting solid gains, led by robust manufacturing and processing activity. On the demand side, investment continued to strengthen, while resilient global demand for electronics and machinery supported faster export growth despite external headwinds, offsetting a slight moderation in private consumption (Exhibit 8).
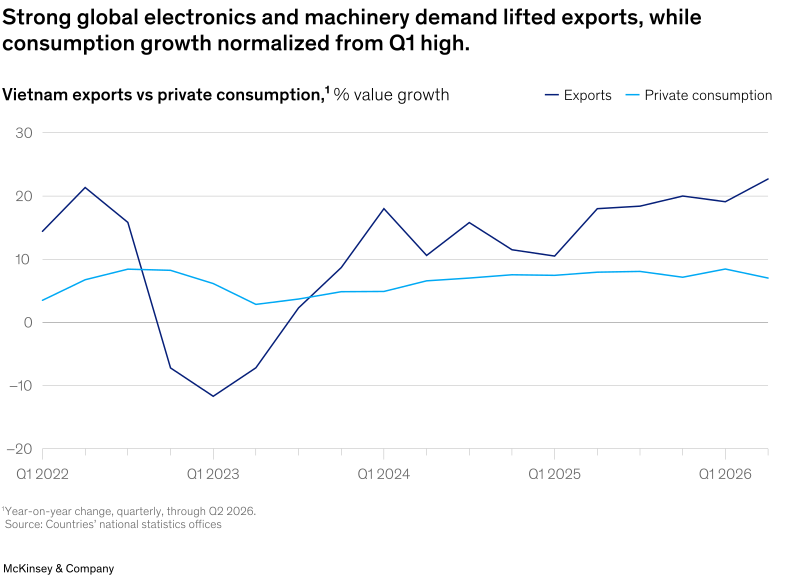
Looking ahead, Vietnam has reaffirmed its target of over 10 percent GDP growth in 2026 despite rising fuel import costs and a widening trade deficit, although doing so will require significantly stronger growth in the second half amid persistent geopolitical and external headwinds.65
Macroeconomic outlook
GDP: Vietnam’s economy expanded by 8.39 percent in the second quarter of 2026, accelerating from 7.8 percent in the previous quarter despite heightened global uncertainty. Growth was underpinned by robust industrial production, resilient domestic demand, strong foreign investment inflows, and increased public infrastructure spending, although rising energy import costs widened the country’s trade deficit.66
Private consumption: Final consumption growth moderated to 7.02 percent in the second quarter from 8.45 percent in the previous quarter. Despite this, underlying domestic demand remains strong, driven by the ongoing recovery in tourism and seasonal spending, alongside a noticeable consumer shift toward sustainable products and experiential leisure.67
Trade: Vietnam’s export growth accelerated to 22.7 percent in the second quarter of 2026, from 19.1 percent in the previous quarter. Electronics, machinery, and mobile phones remained the country’s largest export categories, while textiles and footwear continued to rank among the top five, with these sectors collectively accounting for nearly two-thirds of total exports. China, the European Union, and the United States remained Vietnam’s principal export markets, underscoring the country’s continued integration into global manufacturing and supply chains.68
Industrial activity: Industrial activity gathered pace in the second quarter of 2026, with growth in the Index of Industrial Production (IIP) accelerating to 11.2 percent from 9.0 percent in the previous quarter. Manufacturing output also gained momentum, expanding by 11.4 percent compared with 9.7 percent in the previous quarter, supported by broad-based growth across key industries including food and beverages, electronics, motor vehicles, and furniture.69 PMI rose to 52.9 in July 2026, marking the strongest expansion in five months, as both domestic and export orders strengthened. Easing input cost pressures enabled firms to increase production, expand purchasing activity, and resume hiring, although business confidence remained below pre-conflict levels as the sector continued to face geopolitical uncertainty.70
Labor: The labor market remained stable in the second quarter, with the unemployment rate at 2.23 percent. Employment continued to shift toward the industry and services sectors, and the share of informal employment fell by 0.4 percentage points.71
Prices: Inflation rose 5.25 percent in the second quarter of 2026 from 3.51 percent in the previous quarter, driven by broad-based price increases across all major consumption groups. Transport recorded the sharpest increase of 9.57 percent, reflecting higher petroleum and diesel prices amid elevated global oil prices during the quarter. Despite the pickup, inflationary pressures showed signs of stabilizing toward the end of the quarter, with consumer prices edging down on a month-on-month basis in both May and June.72 Looking ahead, analysts forecast average inflation of 4.8 for 2026, slightly above the government’s 4.5 target, as higher energy prices stemming from the Middle East conflict continue to pose upside risks.73
Financial markets
Currency: The Vietnamese dong remained one of the region’s most stable currencies in the first half of 2026, supported by resilient economic fundamentals and the State Bank of Vietnam’s prudent exchange rate management. As of 2026, the central exchange rate stood at VND25,255 per US dollar, representing a marginal 0.2 percent depreciation from the end of the previous quarter.74
Policy rate: The State Bank of Vietnam has maintained its policy rate, unchanged since June 2023, preserving an accommodative monetary policy stance to support economic growth. The decision was underpinned by contained inflation, a broadly stable Vietnamese dong, and resilient economic activity in the second quarter of 2026. Complementing its accommodative policy stance, the State Bank of Vietnam has introduced targeted lending programs and priority sectors to sustain credit expansion, boost investment, and support the country’s growth objectives for small and medium-size enterprises.75
Capital inflows: Vietnam’s FDI performance remained robust in the second quarter of 2026, underscoring continued investor confidence in the country’s medium-term growth prospects. Realized FDI reached 13.03 billion in the first half of 2026, up 11.2 percent year-on-year and marking the highest first-half disbursement level in five years, while total registered FDI surged 61.0 percent to 34.65 billion. Manufacturing and processing sectors continued to dominate investment inflows, accounting for 82.6 percent of realized FDI, reflecting Vietnam’s enduring appeal as a regional manufacturing hub amid ongoing supply chain diversification.76