Private equity’s new reality

|  | | | |
ON PRIVATE CAPITAL
This isn’t your parents’—or grandparents’—private equity anymore
| | | | | | | | | | | |
| Private equity (PE) is getting harder. For decades, the model was relatively simple: Use cheap debt and count on multiples to expand. It worked so well that returns of 20 percent or even higher were considered standard.
Those days are over.
Over the past few years, PE returns have fallen into the high teens—and in some cases, even lower. For the third consecutive year, the sector has underperformed public markets. While the best funds still outperform broader equities, the underlying economics for PE have shifted.
This isn’t just a rough patch; it’s the sign of a maturing industry. PE is now confronting slower growth and less inviting conditions. Between 2020 and 2025, the number of new firms entering the sector dropped about 18 percent per year globally. Last year, a record 304 firms went inactive. There are now fewer first-time funds than at any point in the past decade. Large players are also consolidating. Funds raising less than $500 million now account for just 13 percent of the market, while megafunds of $5 billion or more have a considerably larger share.
On the surface, 2025 looked like a recovery: Total deal value jumped 19 percent to $2.6 trillion, and the IPO market showed signs of life. But looking below the headlines tells a different story. Deal volume went up, yet deal count fell for the fourth straight year. Venture capital had some significant successes, but that sector was hit hardest overall, dropping 10 percent. And buyouts fell 5 percent.
PE exit values actually increased more than 40 percent in 2025 to $1.2 trillion, even while the number of exits declined by 15 percent. Those dynamics suggest that a few large deals are masking a broader liquidity problem. Cash is staying trapped longer, as more than half of all buyout-backed companies are now held for at least four years. Liquidity—measured by five-year rolling distributions—is at its lowest recorded level.
| | |
| |
| “Your parents’ and grandparents’ PE was a wide open expressway. Today, we’re on an uncharted off road.” | | | |
|
| Investors are changing how they judge success. Our yearly survey of about 300 global limited partners found that distribution to paid-in capital (DPI) is now tied with multiple on invested capital (MOIC) as the most important metric in the eyes of respondents. Yet DPI as a share of total assets was just 6 percent last year, compared with the 16 percent average we saw a few years ago. The quest for cash helps explain why the 2025 secondary market surged by 48 percent.
Prices paid today leave no room for mistakes. Global buyout prices hit a record 11.8 times EBITDA last year. For the biggest deals—those over $500 million—multiples reached 18.1 times EBITDA. Prices are surging in large part because dry powder is getting dryer. About 42 percent of capital committed but not yet deployed is now more than two years old, and pressure to deploy is growing. Because debt is more expensive, leverage fell to just 37 percent. The heftiest prices were paid almost exclusively for “A-grade” companies; “B” and “C” businesses often failed to sell at all.
Our analysis of past time periods shows that overpaying can have serious consequences. For the median buyout deal between 2010 and 2017, there was little difference in returns between funds at the lowest and highest quartiles by entry multiple; they returned 2.8 times and 2.7 times MOIC, respectively. But in buyout transactions occurring between 2018 and 2023, funds with the lowest price per multiple delivered 3.4 times MOIC, while the highest-entry multiple deals were stuck at 2.7 times. The delta is even more stark when looking at the 75th percentile of MOIC within these bands rather than at band medians: 5.5 times for those who paid the lowest prices, versus 3.6 times for those who paid the most.
Successful PE players aren’t relying on cruise control. Instead, they are embracing complexity, such as through take-privates—which rose 43 percent globally and 72 percent in North America—and complex carve-outs, where there is more room to create value. They are also moving into semiliquid structures, which have doubled since 2023 to over $204 billion.
Most important, PE leaders are finding new ways to generate alpha, because the industry is not a superhighway anymore. Larger funds are pulling away from smaller ones. Specialist funds are outperforming generalists. And AI is emerging as the ultimate force multiplier: While only 6 percent of firms currently see high impact from AI, 70 percent expect it to be a major factor in the next few years—sharpening everything from underwriting to operational speed.
Your parents’ and grandparents’ PE was a wide open expressway. Today, we’re on an uncharted off road.
| | | | |
| Share Alexander Edlich’s insights | | | |
|
| |
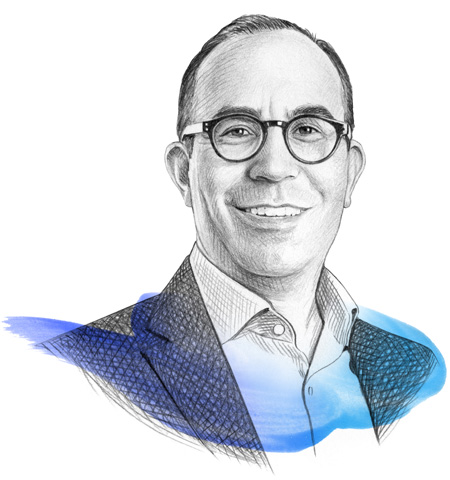
| | Alexander Edlich is a senior partner in McKinsey’s New York office and a senior leader in the Private Capital Practice. | | |
| |
|
|
| |
|
|
|
|
|
Copyright © 2026 | McKinsey & Company, 3 World Trade Center, 175 Greenwich Street, New York, NY 10007
|
|
| |
|